VA Loan No PMI: Monthly Savings for Clarksville Homeowners
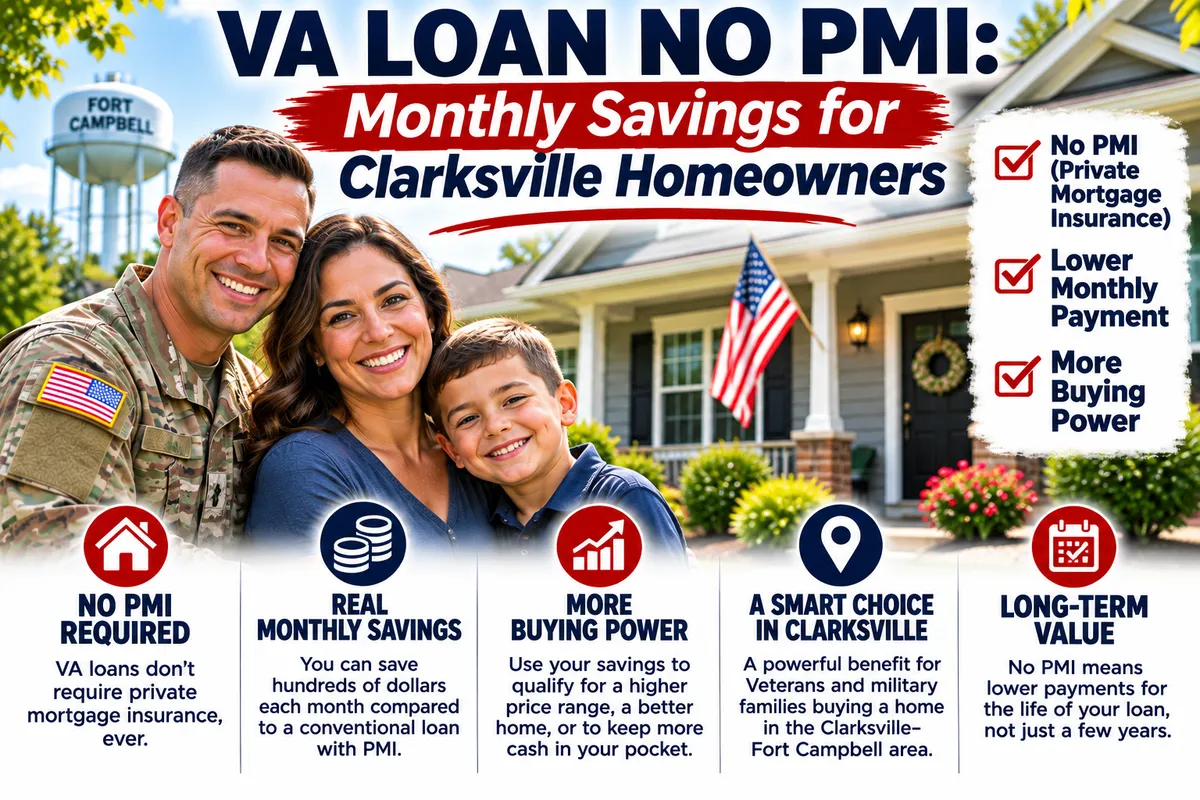
Two offers on the same Clarksville house can look identical on the sticker price and still produce very different monthly payments. The gap often comes down to one line on the loan estimate: private mortgage insurance. VA loans do not charge it, not with a small down payment, not with zero down. That single difference reshapes the budget for military families buying near Fort Campbell, and it is worth understanding exactly where the savings land each month.
What PMI Is and Why VA Loans Skip It
Private mortgage insurance protects the lender if a borrower stops paying. On many loan programs, it is a monthly charge added to principal and interest, and it can stay on the loan for years. VA loans work differently. Program descriptions of VA lending consistently list no PMI as a core feature, alongside the zero down payment option and flexible credit standards.
The exemption is not a temporary promotion or a first-time buyer perk. Sources describing VA loan benefits state plainly that VA loans never charge monthly private mortgage insurance or a monthly mortgage insurance premium, even with 0% down. The rule holds regardless of how little the buyer puts down.
That matters because the loan amount in a Clarksville purchase isn't small, and mortgage insurance is calculated against the balance rather than the buyer's budget. Removing it from the payment changes what a household can comfortably afford, and it changes it from the first payment forward.
The Monthly Difference in Real Terms
How much does the no-PMI rule actually free up? One VA loan calculator source puts the savings for military homebuyers at roughly $150 per month. Treat that as a starting point rather than a promise. The real number depends on the loan amount, the borrower's profile, and what a comparable loan would have charged for mortgage insurance.
The practical way to see your own number is to compare loan estimates side by side. Ask each lender for a written estimate at the same purchase price and down payment, then look for the mortgage insurance line. If one estimate includes it and the VA estimate does not, the difference between those two monthly figures is your savings. That exercise takes a few minutes and replaces guesswork with a concrete figure.
Sources note that lower monthly payments result directly from the no-PMI structure, and those savings add up over time. For a household weighing a move to a new duty station or a first purchase near post, an extra $150 a month is not abstract. It is a utility bill, part of a car payment, or breathing room in a tight relocation budget.

Adding It Up Across Months and Years
A $150 monthly difference becomes about $1,800 across a year. Stretched across a decade, the same figure is roughly $18,000, and that money stays in the household rather than going to an insurance premium. Small monthly numbers hide large totals, which is why it helps to write the annual figure down before deciding between loan types.
One caveat belongs in the math. Mortgage insurance on other loan programs does not necessarily last the entire life of the loan. Hence, the lifetime comparison depends on how long that insurance would otherwise remain in place. The monthly comparison is still the cleanest place to start, because that is the number a budget actually feels. Ask your lender how long mortgage insurance would apply on any non-VA option you are considering so the long-run comparison is honest.
Why Zero Down and No PMI Work Together
The two features reinforce each other. On many low-down-payment programs, a smaller down payment is exactly what triggers a mortgage insurance requirement. With VA eligibility, a zero-down purchase does not create that cost. Program descriptions put it plainly: you can buy a home with no money down, and you never have to pay PMI.
That combination is why VA loans are often described as one of the most powerful tools available to military buyers. A buyer with cash for a down payment can keep it in reserve for moving costs, repairs, or an emergency fund instead of trading it for a lower payment. A buyer without that cash isn't penalized with an added monthly insurance charge. Both paths stay open.
Refinancing and Assumability: Rules That Follow the Loan
The no-PMI structure is not limited to the original purchase. VA program descriptions note that borrowers can refinance up to 100% of the home's value, and that the no-PMI rule applies to VA loans as a category rather than to a single transaction type. If you already have a VA loan, the insurance line isn't part of your payment and doesn't return when you refinance.
VA loans can also be assumable, which means a future buyer may be able to take over the existing loan rather than originate a new one. The assumption process has its own requirements and paperwork, so confirm the details directly with the lender and the VA before counting on it in a sale. A loan with no monthly mortgage insurance is more attractive to pass along, which is part of why the feature draws attention.
What Else to Budget For in Clarksville
Removing PMI does not erase every cost of buying a home. VA loan calculators commonly show funding fee tiers, so the one-time VA funding fee is a real cost to plan for rather than ignore. Ask how it applies in your specific case, since the amount can depend on your service history and whether you have used the benefit before. Confirm the current rules with the VA or your lender rather than relying on a general statement.
Closing costs, prepaid taxes, insurance, and escrow deposits still apply, and some program descriptions advertise no closing costs while others do not. Those offers change over time, so read the terms of any specific program you are quoted. What doesn't change is the monthly insurance line: on a VA loan, there isn't one.
Clarksville buyers connected to Fort Campbell often work against a relocation calendar, which makes early questions more valuable than late ones. Knowing before you shop that PMI is off the table lets you compare offers on the remaining costs and set a realistic monthly ceiling, instead of discovering the difference after you have picked a house.
Questions to Ask Before You Compare Offers
Does this loan estimate include a monthly mortgage insurance or mortgage insurance premium line, and if so, how much is it?
How long would mortgage insurance remain on a non-VA option at my down payment level?
How does the one-time VA funding fee apply to my service history and my previous use of the benefit?
Are there lender fees in this program, and are any of them temporary offers with an expiration date?
If I refinance later, does the new loan keep the same no-PMI structure?
Frequently Asked Questions
Do VA loans really have no PMI at all?
Yes. Sources describing VA loan benefits state that VA loans never charge monthly private mortgage insurance or a monthly mortgage insurance premium, even with a 0% down payment. The exemption is a feature of the program itself, not a temporary promotion, and it applies whether the buyer puts nothing down or makes a larger down payment.
How much can no PMI save each month?
One VA loan calculator source estimates savings around $150 per month for military homebuyers. Your own figure depends on the loan amount, your credit profile, and what a comparable loan would have charged for mortgage insurance. Comparing written loan estimates on the same purchase price is the most reliable way to see your real number.
Is PMI the same thing as the VA funding fee?
No. PMI is a monthly insurance charge, and VA loans do not include one. The VA funding fee is a separate, one-time cost that VA loan calculators commonly break into tiers. Because the amount can vary with your service history and prior use of the benefit, confirm how it applies to you with the VA or your lender.
Can I avoid PMI with a VA jumbo loan?
Program descriptions of VA jumbo loans list no PMI among the features, along with zero down payment options and assumability. Because larger loan amounts can involve additional review, confirm the specifics for your loan size directly with your lender before you make an offer on a Clarksville home.
Does refinancing a VA loan bring PMI back?
VA program descriptions state that borrowers never pay PMI and can refinance up to 100% of the home's value. The no-PMI rule applies to VA loans as a category, so it does not return when you refinance into another VA loan. Ask your lender to confirm the structure of the specific refinance product you are quoted.
The short version for anyone buying near Fort Campbell: no PMI is a permanent monthly advantage, not a discount that expires. Write down what your payment would look like with and without that line, confirm the funding fee and closing costs with your lender, and let the comparison decide which loan makes sense for your household.
Missed the last post? Sango Clarksville TN Homes: Suburban Living for Fort Campbell Families. For more on VA home loans.