Zero Down on a VA Loan Does Not Mean Zero Cost at Closing and Here Is What Veterans Actually Pay
The Distinction Every Veteran Needs to Understand Before Making an Offer
Zero down payment is one of the most powerful features of the VA home loan benefit. It is also one of the most commonly misunderstood. Travis Egan wants veterans to be clear on what zero down actually means and what it does not mean before they sit down at the closing table expecting no out-of-pocket costs whatsoever.
What Zero Down Actually Refers To
Zero down payment means the veteran does not need to put a percentage of the purchase price down at closing. On a conventional loan a buyer might bring three percent, five percent, ten percent, or twenty percent of the purchase price to closing as a down payment. On a VA loan with full entitlement that number is zero. The VA guarantee covers the lender's risk without requiring the veteran to have skin in the game through a cash down payment.
That is a significant and genuine benefit. It is also specifically about the down payment portion of the transaction and nothing else.
What Still Exists at Closing on a VA Loan
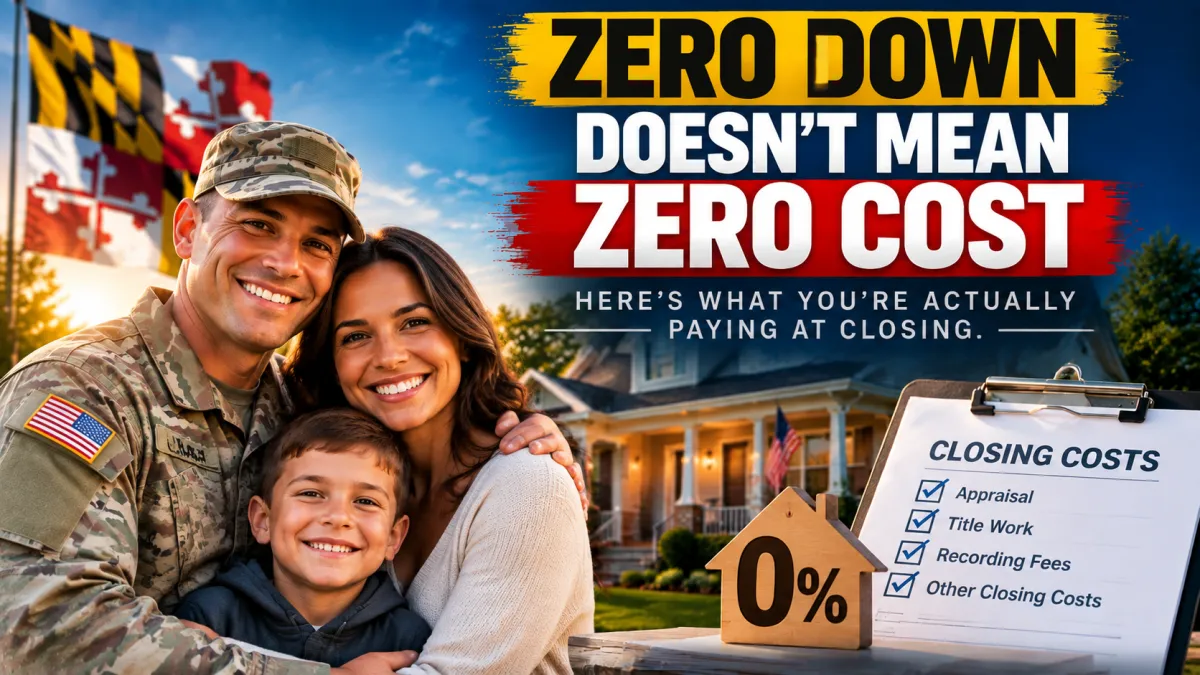
Closing costs are separate from the down payment and they exist on VA loans just as they exist on conventional loans. Appraisal fees. Title work. Recording fees. Lender fees. Prepaid interest. Homeowners insurance. Property tax escrow. These are the costs of completing a real estate transaction and they do not disappear because the down payment is zero.
The good news is that VA loan closing costs are often smaller than conventional loan closing costs for a few specific reasons. The VA funding fee exemption for disabled veterans removes one significant cost entirely. The VA limits certain fees that lenders can charge borrowers. And the overall fee structure tends to be more favorable than what conventional borrowers face.
How Sellers Can Help Cover Closing Costs
In the current market where sellers are more willing to negotiate than they have been in years seller concessions can be applied toward a veteran's closing costs. A seller contribution that covers part or all of the closing costs reduces or eliminates the cash a veteran needs to bring to the table at closing. Combined with zero down payment a well-structured VA offer with seller concessions can get a veteran into a home with very little cash out of pocket.
How Travis Egan Handles This Before You Make an Offer
Travis breaks down the exact closing cost estimate for every veteran before the offer is written rather than letting the closing table be the first time the numbers become real. No surprises. No unexpected cash requirements discovered at the last minute. A clear picture of what closing will actually cost and how much of that sellers can potentially cover given the current market conditions.
Got questions about VA closing costs or any other part of your VA loan? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
ConsumerFinancialProtectionBureau.gov
MilitaryOneSource.mil
MortgageNewsDaily.com
Investopedia.com