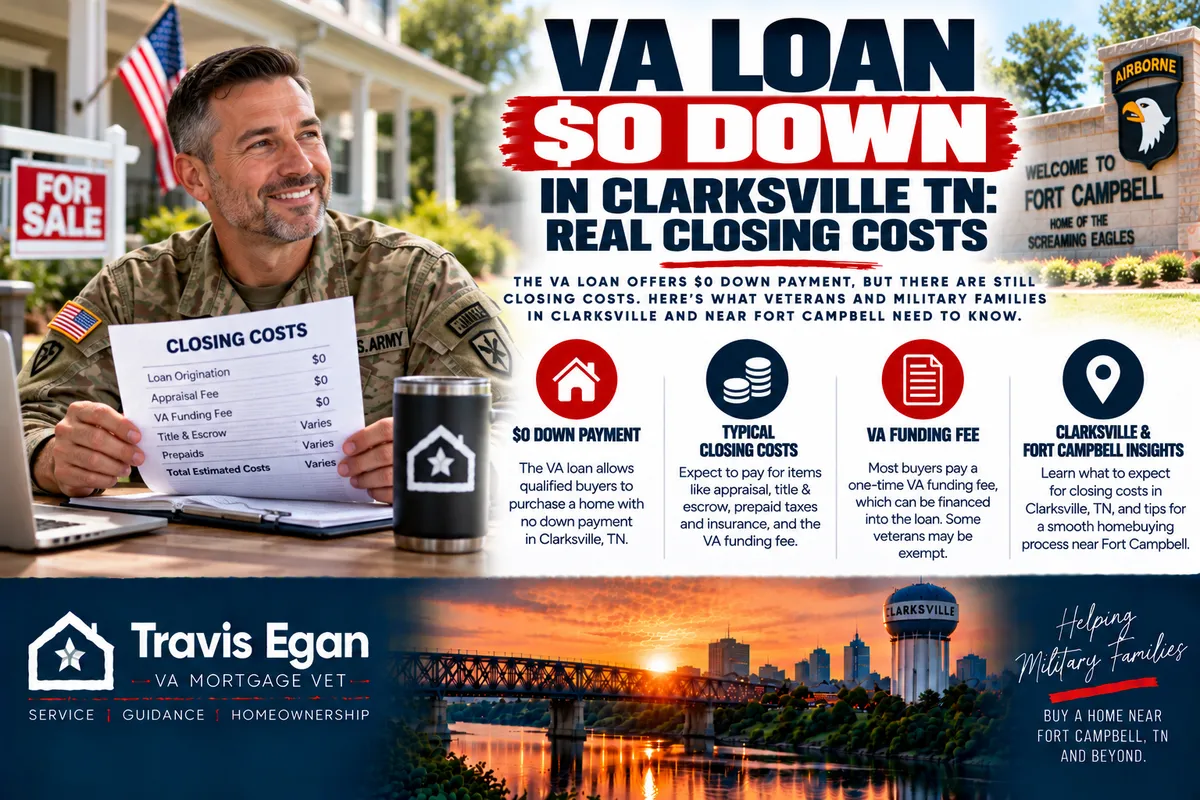
VA Loan $0 Down in Clarksville TN: Real Closing Costs
A VA loan in Clarksville can genuinely put you in a house with no down payment. That part is real, and it is one of the strongest benefits attached to your service. What gets muddled in the retelling is the difference between the down payment and the other money that changes hands before you get the keys. Zero down does not automatically mean zero due at closing.
This is the practical version for buyers around Fort Campbell: what the $0 down benefit covers, what it does not, and how to plan for the cash you will actually bring to the table so closing day does not turn into a scramble.
Why $0 Down and $0 Cash Are Two Different Numbers
Your down payment is the portion of the purchase price you pay out of pocket instead of borrowing. On a VA loan, that number can be zero. The loan also doesn't require private mortgage insurance, which is one reason the monthly payment stays competitive with other low-down-payment options.
Cash to close is a bigger bucket. It includes your down payment, plus the costs of getting the loan, prepaid items, and the escrow deposits your lender collects upfront. Local guidance on Clarksville VA lending makes the same point plainly: a VA loan can mean zero down, but not always zero cash. The down payment line disappears. The other lines still exist, and they still need a funding source.
The Three Buckets of Cash at Closing
Almost every dollar you bring to a VA closing falls into one of three categories. Knowing which is which shows you where you have room to negotiate and where you don't.
The VA funding fee
Most VA loans carry a funding fee that goes to the Department of Veterans Affairs. Consumer materials commonly describe the fee as ranging from as little as 1.25% up to 3.3% of the loan amount, depending on the borrower's situation. Even at the low end, that is a real line item, not a rounding error. Some borrowers may qualify for an exemption, and the fee can sometimes be financed into the loan instead of paid in cash, but both depend on your specific circumstances.
Lender and third-party closing costs
These are the fees charged to originate and process the loan, plus services such as the appraisal, title work, and recording. They vary by lender and transaction so that no one can give you a reliable Clarksville number before a contract and loan estimate. What you can control is comparison. Request a loan estimate from more than one lender on the same purchase scenario and read the sections side by side rather than just the bottom line.
Prepaids and escrow deposits
Prepaids are costs you pay at closing for things that belong to the future. That includes the first year of homeowner's insurance, per diem interest for the days remaining in the month, and the escrow cushion your servicer holds for taxes and insurance. This money is not lender profit. It is timing, and it is usually the piece that catches buyers off guard when they expected to bring nothing at all.

What Each Cost Category Looks Like
Cost category | What it covers | How much room you have |
|---|---|---|
Down payment | The buyer's own share of the purchase price | Can be zero on a VA loan |
VA funding fee | Fee paid to the Department of Veterans Affairs | Described as 1.25% to 3.3% of the loan, depending on the borrower's category |
Lender fees | Origination, underwriting, and processing | Set by the lender, so compare offers |
Third-party services | Appraisal, title, recording, and similar items | Driven by the transaction and the service providers |
Prepaids and escrow | Insurance, per diem interest, and tax and insurance reserves | Tied to your closing date and your policy |
Seller concessions | Closing costs paid on your behalf through negotiation | Available on VA transactions, subject to the contract |
How Clarksville Buyers Reduce the Cash They Bring
The gap between zero down and zero cash can often be narrowed. None of these moves requires a different loan program, just a different approach to the paperwork.
Ask the seller to cover closing costs. Sellers can pay your VA loan closing costs. In a negotiation where you might otherwise push for a lower price, redirect that leverage into closing-cost help to keep your savings intact while keeping the loan structure clean.
Compare loan estimates line by line. Lender-controlled fees are the ones you can shop. Title and appraisal charges are harder to move, but you should still understand them before you commit.
Confirm your funding fee category early. If an exemption applies to you, find out before the closing disclosure appears rather than after.
Ask about local assistance. Down payment assistance is advertised in the Clarksville market, with figures cited as high as $15,000. Availability, eligibility, and terms change often, so confirm details with the program administrator and make sure any assistance works with your VA loan.
Watch your closing date. Per diem interest is charged for the days left in the month, so the calendar has a small but real effect on your prepaid total.
Why the 0% Down Benefit Matters Around Fort Campbell
Clarksville's housing market is shaped by the installation next door. Orders arrive on a timeline that has nothing to do with how long it takes a family to build a savings cushion, and a PCS move can drain whatever cushion already exists. That is exactly the situation a zero down loan was designed to address.
The benefit is not small. A 2025 PR Newswire report found that 74% of first-time VA loan users put 0% down, compared with a 12% median down payment for conventional first-time buyers. The same report concluded that a 0% down VA loan can put first-time buyers into a home 4.4 years sooner than a typical conventional loan. For a household relocating to Fort Campbell, that difference is measured in tours of duty, not just months.
What $0 Down Does Not Cover
Setting realistic expectations protects you from a bad surprise two days before signing. The zero down feature applies to the purchase price. It does not create money for everything else.
Moving costs, temporary lodging, and utility deposits connected to the relocation
Repairs the seller declines to address after the inspection
Furniture, appliances, and the ordinary setup costs of a new household
Any gap that emerges if an appraisal changes the shape of the deal, which should be discussed with your loan officer as soon as it happens
Budgeting for those items separately keeps the mortgage conversation honest. A loan officer can tell you what the loan will cover. Only you can decide how much cash you want left in the account after closing.
Questions to Ask Before You Commit
What funding fee applies to my situation, and is it being financed or paid at closing?
What is my total cash to close, not just my down payment?
Which fees are set by the lender, and which are third-party charges I can compare?
How much seller concession is built into this contract, and what does it offset?
What happens to my numbers if the closing date moves by a week?
Frequently Asked Questions
Does a VA loan really require zero down in Clarksville?
Yes, a VA loan can be structured with no down payment. That is one of the program's core features and why so many first-time buyers use it. The zero-down benefit applies to the purchase price. Closing costs, prepaids, and the funding fee are separate, and you may still need cash or to negotiate them.
Can the seller pay my closing costs on a VA loan?
Sellers can pay your closing costs on a VA loan. That concession is negotiated as part of your offer and written into the contract. It is one of the most effective ways to keep your own savings intact while still going zero down, and it is worth discussing with your agent before you submit an offer.
How much is the VA funding fee?
Consumer materials describe the fee as ranging from as little as 1.25% up to 3.3% of the loan amount, depending on the borrower's category. Some borrowers may be exempt, and the fee can sometimes be financed rather than paid in cash. Confirm your specific category with your loan officer or the VA before you finalize your cash plan.
Will I bring no money at all to closing?
Not necessarily. Zero down removes the down payment, but lender fees, third-party services, insurance, per diem interest, and escrow deposits can still apply. Seller concessions can reduce much of that. The honest answer is that your cash to close depends on your contract, your lender, and your closing date, so ask for the number in writing.
Do VA loans require private mortgage insurance?
No. VA loans don't require private mortgage insurance, which is a meaningful monthly difference compared with other low-down-payment programs. The funding fee is a separate one-time cost paid to the Department of Veterans Affairs. Ask your loan officer to show both the fee and the monthly payment side by side so you can compare offers accurately.
The cleanest way to plan a Clarksville VA purchase is to treat zero down as a benefit that protects your savings, not as a promise that closing is free. Get your funding fee category confirmed, get a loan estimate in hand, and negotiate seller help where the market allows it. Do that, and the number on your closing disclosure will match what you planned.
Missed the last post? VA Loan Eligibility for Surviving Spouses Near Fort Campbell. For more on VA home loans.