VA Loan Clarksville TN: What Does It Really Cost to Buy?
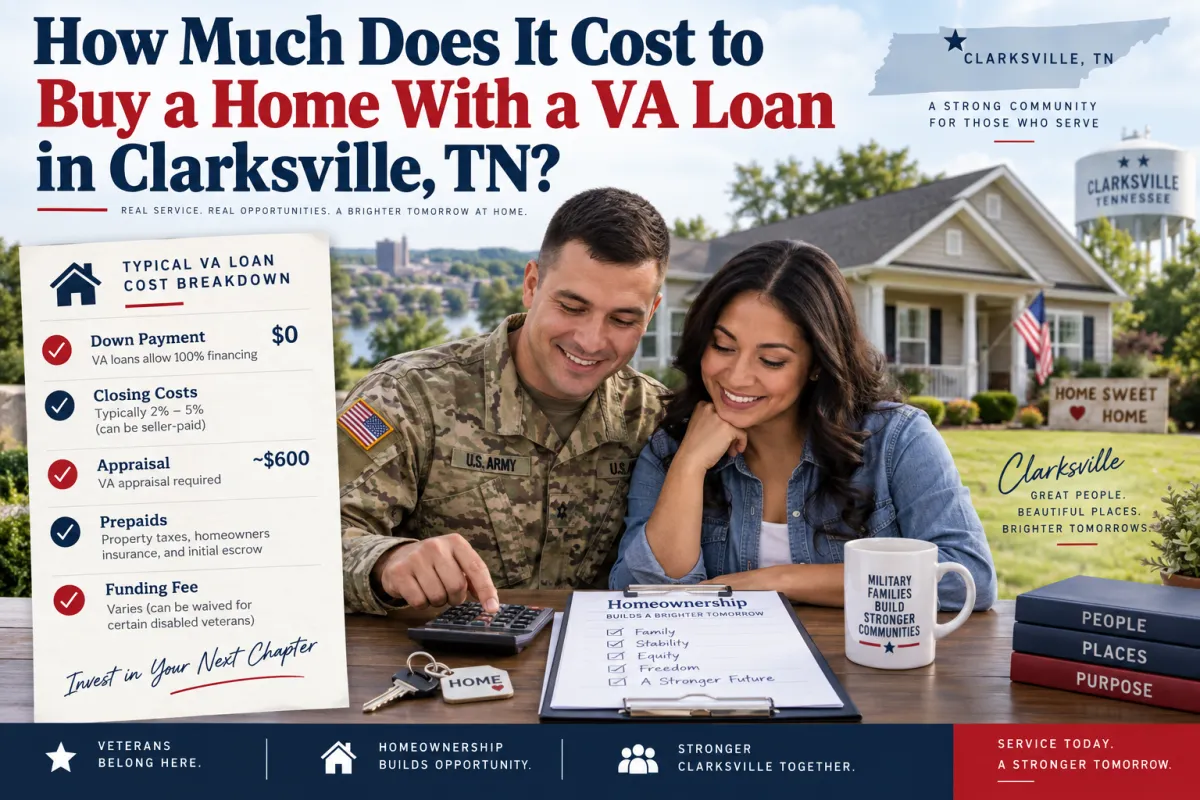
The short answer is that a VA loan in Clarksville, Tennessee can require no down payment, but it rarely requires zero cash at closing. Most buyers still bring money for lender fees, title and settlement charges, prepaid county taxes and homeowners insurance, and sometimes the VA funding fee. Subtract any seller concessions, lender credits, and the earnest money you already deposited to find your real cash to close.
Because that number changes with every house, every lender, and every negotiated contract, there is no single price tag for buying in Clarksville with a VA loan. What you can do is understand each piece of the puzzle, then ask for a written estimate before you write an offer.
How Much Money Do You Need to Buy a Home With a VA Loan in Clarksville, TN?
For a buyer with full VA entitlement, the down payment can be $0. The cash you actually bring to the closing table is a separate calculation, and these items drive it:
The purchase price you agree to
Lender fees, including origination and processing charges
Title search, title insurance, settlement, and recording charges
Prepaid property taxes and the first year of homeowners insurance
Escrow reserves your lender collects upfront
Whether the VA funding fee applies to you, and whether you finance it or pay it
Seller-paid costs negotiated in your contract
Lender credits applied to your closing costs
Earnest money you already put down
Any one of those can shift your total by several hundred or several thousand dollars. That is why a personalized estimate from a lender who works VA files every week in the Fort Campbell area beats any generic online calculator.
The five terms buyers mix up.
Most confusion around VA loan cash to close comes from treating five different things as one number. They are not.
Term | What it means | Who controls it |
|---|---|---|
Down payment | The percentage of the purchase price you pay upfront. On a VA purchase with full entitlement, this can be $0. | VA program rules and your entitlement |
Closing costs | Fees charged to originate, underwrite, title, and record your loan and the property transfer. | Your lender, title company, and local recording offices |
Prepaids and escrow | Money collected at closing for future taxes and insurance, plus daily interest on the new loan. | Your county tax schedule, insurance premium, and closing date |
VA funding fee | A one-time fee the VA charges on most VA loans. | The VA, based on your service history and exemption status |
Cash to close | The final wired or certified amount you bring after credits and deposits are applied. | The combination of everything above |
Once you separate these five, the question "how much does a VA loan cost in Clarksville" becomes answerable. You are not solving for a down payment. You are solving for closing costs plus prepaids plus funding fee, minus credits and deposits.
Does a VA Loan Really Require Zero Down in Clarksville?
Yes, VA loans offer 100 percent financing with no down payment for eligible buyers with full entitlement. That is one reason active-duty service members stationed at Fort Campbell and veterans settling in Montgomery County use them so often. A PCS move already comes with enough expenses without adding a down payment.
Two cautions matter here. First, zero down refers only to the down payment. It says nothing about closing costs, prepaid taxes, or insurance. Second, not every borrower has full entitlement available, and a lender may still require a down payment on some files. If you have used a VA loan before, or you are buying with a non-veteran co-borrower, ask your lender to confirm your entitlement before you start shopping.
What Closing Costs Does a VA Buyer Pay in Clarksville, TN?
A VA buyer pays the same categories of closing costs as any other financed buyer, unless the seller or lender agrees to cover them. Those costs fall into three buckets.
Lender and origination fees
This is what your mortgage company charges to process, underwrite, and fund the loan. It can include an origination charge, an underwriting fee, a processing fee, an appraisal fee, a credit report fee, and a flood certification. Discount points, if you choose to buy the rate down, also live here.
Title, settlement, and recording costs
Tennessee transactions typically involve a title search, title insurance, a settlement or closing fee, and recording charges with the county. These costs tie to the property and the purchase price, not your loan type, so they show up on VA, conventional, and FHA files alike. The dollar amount varies by title company and by what the contract says the seller will pay.
Items you should verify with your lender
VA guidelines limit certain charges, and some fees that appear on a standard Loan Estimate may be handled differently on a VA loan. Rather than guessing, ask your loan officer to walk you through your Loan Estimate line by line and mark which fees are buyer-paid and which are negotiable. That conversation takes fifteen minutes and can change your offer strategy.
What Costs Can a Seller Pay for a VA Buyer?
Sellers can contribute toward a VA buyer's closing costs, prepaid items, and other allowable expenses through a negotiated credit. This is one of the most effective ways to reduce cash to close, and it costs the buyer nothing except negotiating leverage.
What are VA seller concessions?
Seller concessions are credits the seller agrees to pay on the buyer's behalf at closing. They are written into the purchase contract as a dollar amount or a percentage of the purchase price and then shown on the Closing Disclosure. VA rules govern what seller concessions may cover and how they are counted, and they limit what a seller may pay. Confirm the current rules with your lender before you structure an offer.
In practice, Clarksville buyers often ask sellers to cover some or all of the buyer's closing costs, prepaid taxes, and insurance reserves. In a balanced market, sellers may agree. In a competitive market, they may not. That is a negotiation, not a guarantee, and it changes from street to street.
How Does the VA Funding Fee Affect Cash to Close?
The VA funding fee is a one-time charge the VA assesses on most VA loans. It exists so the program can keep running without a monthly mortgage insurance premium. The amount depends on factors such as your down payment, whether this is your first VA loan or a subsequent use, and the type of service you performed.
Here's what matters for cash to close: many buyers finance the funding fee into the loan rather than paying it in cash at closing. That keeps money in your pocket on closing day, but it increases your loan balance and raises the amount you finance. If you would rather pay it upfront, you can, as long as you plan for it. Either way, ask your lender for the exact figure for your file.
Who may be exempt from the VA funding fee?
Some borrowers are exempt from the funding fee entirely. Exemptions generally apply to veterans who receive VA disability compensation, and to certain surviving spouses. If you believe you qualify, request your Certificate of Eligibility and confirm your exemption status with your lender early in the process. On a large loan, that exemption can remove a meaningful chunk from your total cost.
What Prepaid Expenses Should Clarksville Buyers Expect?
Prepaid expenses are collected at closing to fund your escrow account and cover costs that relate to the calendar rather than the loan. Clarksville buyers should plan for property taxes, the first year of homeowners insurance, per diem interest from your closing date to the end of the month, and lender-required escrow reserves.
Three variables drive how much this comes to. The tax amount depends on the assessed value and the local tax rate, which is why it changes from property to property. The insurance premium depends on the home's age, construction, and claims history. The escrow cushion depends on your lender's own policy. If the home is in a neighborhood with a homeowners association, expect HOA dues and possibly transfer fees. None of these are VA-specific, but they all show up in your cash-to-close.
What Happens to Earnest Money at Closing?
Earnest money is a good-faith deposit you put down when your offer is accepted. It is not an extra cost. At closing, your earnest money is credited back to you and applied to your total cash to close, reducing the amount you have to wire.
The deposit size is negotiable and varies by market, so ask your real estate agent what is typical for the Clarksville price range you are shopping in. More important than the amount is protecting it. Make sure your contract includes financing and inspection contingencies, and understand how the appraisal process works on a VA loan. If you terminate under a valid contingency, you generally get the deposit back. If you walk away outside your contingencies, you may not get it back.
Can Lender Credits Reduce Cash Needed at Closing?
Yes, lender credits reduce the cash you bring to closing. A lender credit is money your mortgage company applies toward your closing costs, usually in exchange for accepting a slightly higher interest rate. It is a trade, not a gift: you pay less today and more over the life of the loan.
Do not confuse lender credits with seller concessions. A lender credit comes from your mortgage company. A seller concession comes from the seller. Both appear as credits on your Closing Disclosure, and both lower your bottom line. If covering cash to close is the priority, ask your loan officer to show you the same scenario with and without a lender credit so you can compare the monthly payment against the upfront savings.
How Much Cash Might a Buyer Need on a $250,000, $300,000, $350,000, or $400,000 Clarksville Home?
There is no fixed answer, because the cash needed depends on your specific lender fees, title charges, tax and insurance figures, funding fee status, and negotiated credits. The loan size and funding fee scale predictably, both of which rise with the purchase price.
The table below is a planning framework, not a quote. Use it to organize the conversation with your lender.
Purchase price | VA down payment with full entitlement | What changes as the price rises |
|---|---|---|
$250,000 | $0 | Lowest loan amount in this group, so if the funding fee is financed, it adds the smallest amount to the balance |
$300,000 | $0 | Closing costs tied to price, such as title insurance and recording, tend to increase |
$350,000 | $0 | Prepaid tax reserves are generally higher because assessed value is higher |
$400,000 | $0 | The loan amount is largest here, and the funding fee percentage applies to a larger base. |
These figures are illustrations only. Actual closing costs vary based on the property, the lender, taxes, insurance, title costs, negotiated seller credits, and current market conditions. Two buyers purchasing identical homes at the same price in Clarksville can end up with very different cash to close, simply because one negotiated seller concessions and the other did not.
How Fort Campbell Buyers Can Get an Accurate Cash-to-Close Number
Start with a full pre-approval, not a quick prequalification. A pre-approval requires documentation, which means the numbers you receive are grounded in your actual income, debts, and entitlement. That matters when you are on a PCS timeline and need to make a confident offer fast.
Then ask for a written estimate of cash to close on a specific price range, not a general range. Once you are under contract, compare that estimate against your official Loan Estimate and your Closing Disclosure. If the numbers move, ask why. Travis Egan is a Marine Corps veteran and VA mortgage specialist based in Clarksville who works with active-duty service members, veterans, and military families connected to Fort Campbell, and he can walk you through the same scenario at several price points before you commit.
Get Your Clarksville Cash-to-Close Estimate Before You Make an Offer
Knowing your number before you shop changes how you negotiate. You will know whether you need seller concessions, whether a lender credit makes sense, and how much room you have in your monthly budget. Reach out for a personalized estimate of expected cash to close in the Clarksville price range you are targeting, and ask about the free VA Homebuyer's Guide while you are at it.
Frequently Asked Questions
Can I buy a home in Clarksville with a VA loan and no money down?
Yes, if you have full VA entitlement, the down payment can be $0. That does not remove closing costs, prepaid taxes, insurance reserves, or the funding fee. Many buyers offset those with seller concessions or lender credits. Ask your lender for a written cash-to-close estimate so you know exactly what to plan for before you make an offer on a Clarksville home.
Can the seller pay all of my VA closing costs?
Sometimes, but it depends on the contract and on VA rules about what seller concessions may cover. Sellers can contribute toward buyer closing costs and prepaid items within program limits. Whether a Clarksville seller agrees depends on the home, the market, and your offer. Confirm the current rules with your lender before structuring your request.
Can I roll closing costs into a VA purchase loan?
Generally, you cannot roll ordinary closing costs into a VA purchase loan the way you might add them to a car loan. Instead, many buyers finance the VA funding fee into the loan and negotiate seller concessions or lender credits to cover other costs. Your lender can show you which specific items you can finance on your file.
Does the VA funding fee have to be paid in cash?
No. The funding fee is often financed into the loan, so it doesn't require cash at closing, though it does increase your loan balance and monthly payment. Some buyers choose to pay it upfront instead. Borrowers who qualify for a VA funding fee exemption do not pay it.
How much earnest money do I need for a VA loan in Clarksville?
The amount is negotiable and depends on local custom and the price range you are shopping in. It is not a VA requirement. What matters more is protecting the deposit with proper contingencies. At closing, your earnest money is credited back to you and reduces the cash you need to bring, so it is a deposit, not an extra fee.
Missed the last post? Check out VA Loan With Bad Credit: Collections and 580 Credit Scores. For more on VA home loans.