Sellers Can Help VA Buyers Pay Closing Costs and Here Is Exactly How Much They Can Contribute
The VA Closing Cost Myth That Is Costing Veterans Real Money
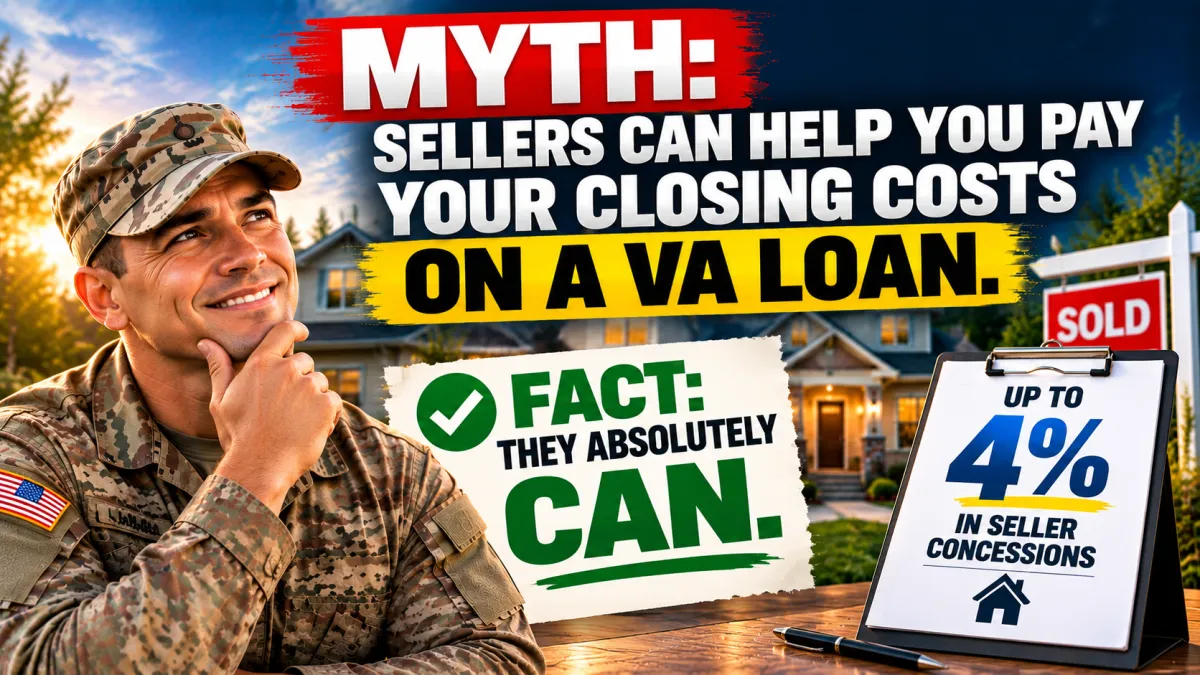
A persistent misconception is that sellers cannot or will not help VA buyers cover closing costs. It is not true, and believing it without question can cost veterans thousands of dollars they never needed to spend.
Travis Egan wants every VA buyer to understand what the actual guidelines say before their next offer is written.
What VA Guidelines Actually Allow
VA guidelines allow sellers to pay up to 4% of the loan amount in concessions, in addition to covering standard closing costs and discount points. That four percent is separate from and on top of the closing costs and points the seller can already contribute.
On a $400,000 loan, 4% equals $16,000 in potential seller concessions before standard closing cost contributions are even considered. That is a meaningful amount of money that can dramatically reduce or eliminate the cash a veteran needs to bring to the closing table beyond the down payment.
What Seller Concessions Can Cover
The VA's concession allowance covers a range of costs that directly reduce the buyer's out-of-pocket expenses. Seller concessions can cover the VA funding fee, one of the larger closing costs on a VA loan for veterans who are not exempt. Prepaid items like homeowners insurance and prepaid interest can also be addressed how these concessions are structured matters and is worth understanding before you write an offer, not after.
Why This Conversation Needs to Happen Before the Offer
Travis regularly helps buyers' agents negotiate seller concessions into offers. It is a standard part of structuring a VA offer in the current market, where sellers have more motivation to work with buyers than they did at the peak of the seller's market.
If the agent representing a VA buyer hasn't raised the question of seller concessions before writing an offer, that is a conversation worth starting. Negotiate this in the offer itself, not after acceptance, when the deal structure is already set and leverage shifts.
If you have been told about seller concessions and/or what's available on VA loans, or if your agent hasn't raised the topic before writing offers, reach out to Travis Egan directly. He will walk through exactly what is available in your specific situation and how to make sure it gets into the offer where it can actually help. DM Travis anytime. He is here to help. Semper Fi.
Missed the last post? How Long Does a VA Loan Actually Take From Offer to Keys and Here Is the Honest Answer. For more on VA home loans.
Sources
VA.gov
ConsumerFinancialProtectionBureau.gov
MilitaryOneSource.mil
MortgageNewsDaily.com
Investopedia.com