Can You Qualify for a VA Loan on BAH Alone?
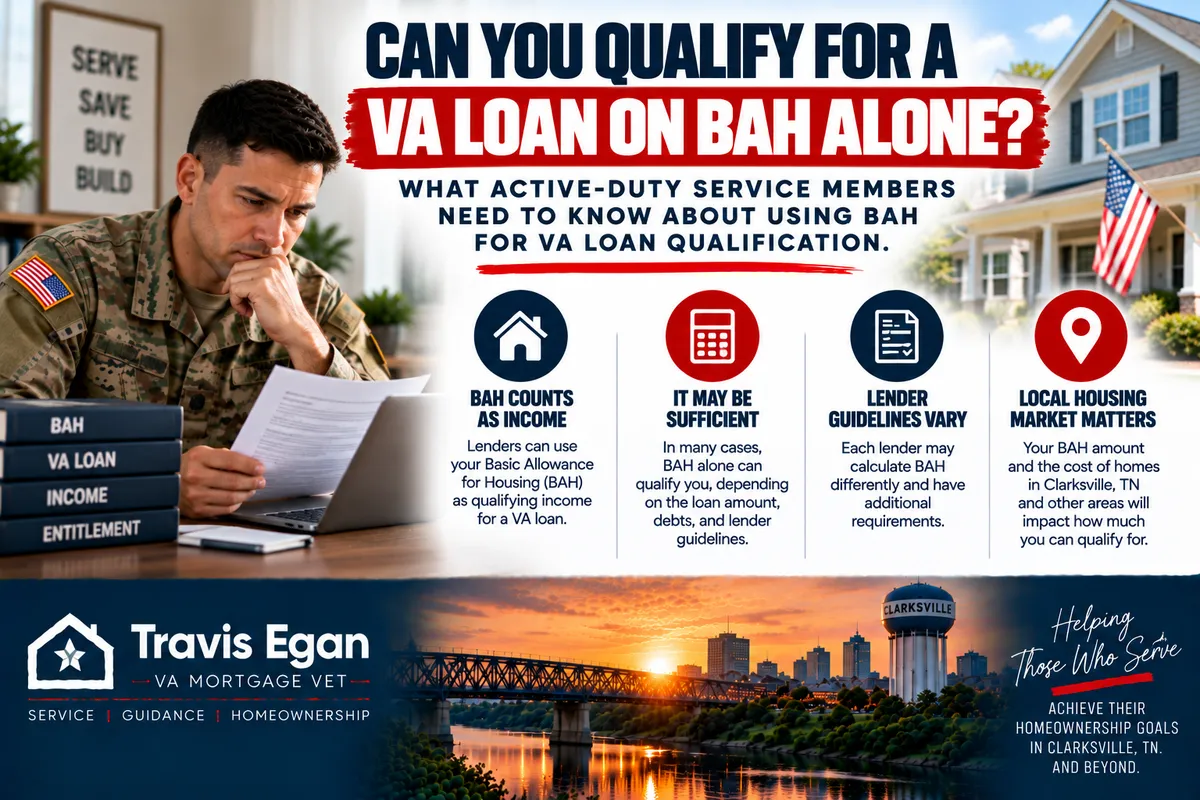
Yes, Basic Allowance for Housing (BAH) can generally be counted as qualifying income for a VA loan, and lenders do consider it when the allowance is properly verified. BAH alone does not automatically qualify you for a mortgage, though. A lender still reviews your total qualifying income, monthly debts, VA residual income, credit history, military status, and the full housing payment on the property you want to buy. BAH strengthens your file. It rarely carries the file by itself.
That distinction matters for active-duty service members and military families who assume a housing allowance will translate directly into a mortgage approval. It can help a great deal, especially when paired with a VA loan, which typically offers a 0% down payment option and seller-paid or lender-covered closing costs. It can't replace the underwriting process. The sections below walk through how BAH is verified, why it is treated differently from base pay, when it can change, and what else a lender weighs before issuing an approval.
Can You Qualify for a VA Loan With BAH Income?
In most cases, yes. VA underwriting guidance states that a military quarters allowance may count as effective income if it is properly verified. That single sentence supports counting BAH on a VA loan application, which is why lenders consistently accept the allowance as a legitimate income source rather than a temporary perk.
What the guidance does not do is spell out a single required method of verification. As a result, lenders apply their own documentation standards. Some want a current Leave and Earnings Statement plus written confirmation that the allowance will continue. Others want additional paperwork tied to your duty station or orders. The practical takeaway is that BAH can count, but the file has to prove the amount and prove continuance.
Qualifying income is also only one input. A lender also examines:
Your total qualifying income from all acceptable sources, not just BAH
Your recurring monthly debts, including auto loans, student loans, and credit cards
VA residual income, which measures what remains after major obligations are paid
Credit history and any derogatory accounts
Your employment or military status, including time remaining on active duty
The complete proposed housing payment, from principal and interest to taxes and insurance
What BAH Is and How It Shows Up on Your LES
Basic Allowance for Housing is a non-taxable monthly stipend paid to active-duty military members who do not reside in government-owned housing. It is intended to offset the housing costs in the area where you are stationed, so the amount is tied to location rather than a flat national rate.
On your Leave and Earnings Statement, BAH normally appears as its own line item separate from base pay and separate from Basic Allowance for Subsistence. That separation is useful during underwriting. A lender can point to the exact entitlement, confirm the pay grade and dependency status that drive it, and then determine whether the same amount will continue after closing.
Because BAH is an allowance rather than wages, it may not be treated the same as taxable earnings. Lenders look for it as a distinct entitlement and compare what appears on the LES with what the allowance should be at the duty station tied to the loan. A mortgage calculator built around the VA residual income standard can help you see early how much room you have, but the LES settles the question.
Why Non-Taxable Income Gets Extra Attention
BAH is generally non-taxable income, which is one reason it is attractive on a mortgage application. Federal income tax doesn't reduce a dollar of BAH the way it reduces a dollar of base pay so that it can stretch further toward a housing payment.
Non-taxable income may still be treated differently from taxable wages during qualification. Lenders want the verified amount to reflect what you will actually receive going forward, not an estimate based on a prior year or a different duty station. That is why underwriting focuses on continuance. An allowance that is scheduled to end, that depends on a housing arrangement about to change, or that is tied to a location you are leaving does not carry the same weight as one expected to continue through the loan period.
BAH Changes With Duty Station, Rank, Dependents, and Housing
One of the biggest misunderstandings about BAH is that it is a fixed number. It is not. The allowance can change when a service member changes duty stations, when rank or pay grade changes, when dependency status changes, or when the housing situation changes, such as moving into or out of government-owned housing.
For a lender, that volatility creates a specific requirement. The BAH amount used in qualification should be the amount expected to continue after the home purchase, not simply whatever figure happens to appear on the LES that month. Getting this wrong in either direction causes problems. If the lender uses an amount that will drop after closing, the borrower can end up stretched. If the lender ignores an increase that is already documented, the borrower may qualify for less than they should.
Why BAH Alone May Not Be Enough
Receiving BAH does not mean a specific mortgage payment is affordable. The allowance has to be measured against the entire housing expense and the rest of the household budget.
The Full Monthly Housing Payment
The payment a lender evaluates is rarely just principal and interest. It also includes property taxes, homeowners insurance, and HOA dues when the property has a homeowners association. Those components can vary widely from one neighborhood to the next even when the loan amount is identical. A home that looks comfortable on principal and interest alone can become tight once taxes, insurance, and association dues are added.
Then there are the debts outside the mortgage. Auto loans, student loans, personal loans, credit card minimums, and any other recurring obligation all count toward the borrower's monthly obligations. Each one reduces how much of the BAH and base pay can realistically go toward housing.
VA Residual Income
VA residual income is a second review layer that runs alongside the debt-to-income ratio. Even when the ratio looks acceptable on paper, the lender must also determine whether sufficient income remains after major monthly obligations are paid. The mortgage payment, taxes, insurance, and other debts come out first, and what is left must cover everyday living costs.
This is why two borrowers with identical ratios can receive different answers. Residual income looks at the household's actual breathing room rather than a percentage. The specific thresholds and how they are applied come from VA guidance, so confirm current standards with your lender or the VA directly rather than relying on rules of thumb you hear secondhand.
Two Service Members, Same BAH, Different Purchasing Power
Consider two service members stationed at the same installation, in the same pay grade, with the same dependency status, receiving the same BAH amount. On paper, their income looks identical. Their borrowing power does not have to be.
The first service member carries one modest auto loan, keeps credit card balances low, and has no other installment debt. After the full housing payment is subtracted, a meaningful share of monthly income remains, which supports residual income and leaves room in the debt-to-income ratio. This borrower can often look at a higher price range without straining the budget.
The second service member receives the same BAH but drives a newer vehicle with a larger payment, carries several credit cards with balances near their limits, and is paying down a personal loan. Those obligations are subtracted before housing is considered, which shrinks the housing payment the file can support. The same BAH now points to a lower price range, and in some cases the residual income test becomes the deciding factor rather than the debt-to-income ratio.
Neither borrower did anything wrong. The lesson is that BAH is a component of purchasing power, not a measure of it. The debts attached to that allowance determine how far it actually reaches. Paying down revolving balances before applying is one of the most direct ways to change the math.
Base Pay, BAS, Special Pay, and Other Military Income
BAH is often only one piece of a service member's qualifying income. Lenders can also consider income from active military employment and certain military benefits, and in most files BAH is evaluated alongside other compensation rather than in isolation.
Base pay typically forms the backbone of the file because it is steady, documented, and expected to continue. Basic Allowance for Subsistence may also be reviewed as a separate non-taxable entitlement. Certain special pays tied to a service member's role, assignment, or conditions of duty can be included when they are documented and expected to continue. Bonus and incentive pay may be evaluated with attention to whether it is recurring or one-time. You can also consider civilian spouse income, subject to its own verification and continuance rules.
Because these sources are not interchangeable, it helps to think in terms of verified continuance. The question is not only how much money arrives each month, but how reliably that amount will keep arriving after closing.
PCS Moves: Which BAH Amount the Lender Uses
A permanent change of station is one of the most common times BAH changes because the allowance is tied to the location where a service member is stationed. A move to a new duty station means a new allowance figure, which may be higher or lower than the current one.
For a purchase loan tied to a PCS, the lender must verify the expected BAH at the new location rather than assume the current duty station's allowance will continue. PCS orders and related documentation often play a central role in that verification, because they show both the new duty station and the timeline. Getting ahead of this early keeps the file moving. Service members who assume their current allowance will carry over to a new assignment can run into surprises during underwriting, especially when the new location pays less.
A BAH-free baseline is a useful exercise during a PCS. List the income sources that exist independently of the allowance, then build a second budget that includes the expected BAH at the new duty station. The gap between those two numbers shows how much of the housing plan depends on the allowance alone.
Occupancy Requirements for a VA Purchase Loan
A VA purchase loan is generally intended for the borrower's primary residence. That means the borrower has to satisfy the applicable VA occupancy requirements, which are tied to living in the home rather than treating it purely as an investment. Confirm the current requirement language with the VA or with your lender before you commit to a property, since occupancy rules affect how a home can be used after closing.
What Documents Will a Lender Need to Verify BAH?
Documentation is where a BAH-based file succeeds or stalls. Lenders typically rely on a short list of records that establish both the amount and its continuation.
A current Leave and Earnings Statement showing BAH as a distinct line item, along with pay grade and dependency status
Military orders when applicable, particularly for a PCS purchase or when the duty station is changing
Verification of service, which confirms active-duty status and the details tied to the commission
Documentation showing the BAH amount expected to continue after the purchase, rather than only the amount currently paid
Because the VA guidance calls for the allowance to be properly verified without prescribing one method, lenders may request additional records. Ask upfront what your loan officer needs, and provide the full LES rather than a screenshot of one line. A complete document is easier to underwrite than a partial one, and missing pages are one of the most common causes of delay.
Income Sources at a Glance
Income Source | Can It Potentially Count? | What the Lender Reviews |
|---|---|---|
Base pay | Yes | Active-duty status, LES history, documented continuance |
BAH | Yes, when properly verified | LES line item, pay grade, dependency status, duty station, expected amount after closing |
BAS | Yes, as a separate non-taxable entitlement | LES documentation and confirmed continuance |
Special pay | Often, depending on the type and continuance | Documentation of the pay, its purpose, and whether it is expected to continue |
Bonus or incentive pay | Sometimes, with conditions | Whether it is recurring or one-time, plus supporting paperwork |
Civilian spouse income | Yes, under its own guidelines | Employment history, pay documentation, and continuance |
How Much House Can You Afford With BAH?
No universal home price corresponds to a given BAH amount. BAH varies by duty station, pay grade, and dependency status. On top of that, the loan interest rate, local property taxes, homeowners insurance premiums, HOA dues, other monthly debts, and your residual income all affect the answer. Two families receiving the same allowance in different states can qualify for very different price ranges.
Work the numbers in the right order. Start with the full monthly housing payment, not the loan amount; add up every recurring debt; and see what remains. Then compare that result against the BAH and other income you expect to receive after closing. VA loans typically offer a 0% down payment option, which removes a common barrier, but it doesn't change the monthly obligation underwriting measures.
It also helps to know where you stand on entitlement. Your Certificate of Eligibility shows your entitlement for the VA home loan guaranty, and VA publishes current entitlement and loan-limit information that lenders use alongside the appraisal. Review those figures with a loan officer who regularly works with military borrowers to turn an allowance into a realistic price range quickly.
Frequently Asked Questions
Does BAH count as income for a VA loan?
Yes, in most cases. VA guidance lets you include a military quarters allowance as effective income when it is properly verified, and lenders regularly count BAH on VA loan applications. The allowance has to be documented and expected to continue after closing. Lenders typically evaluate base pay, BAS, and other verified military compensation alongside it rather than ignoring it.
Can I buy a house with BAH only and no other income?
A file built on BAH alone is difficult, because underwriting also reviews your monthly debts, credit history, military status, and residual income. Most approvals rely on total qualifying income, which usually includes base pay and other verified compensation. If BAH is your only documented source, expect a lender to look closely at continuance and at how much remains after obligations are paid.
What happens to my BAH when I PCS?
BAH is tied to location, so a permanent change of station usually changes the amount. A lender reviewing a purchase connected to your move needs the allowance expected at the new duty station, not the amount on your current Leave and Earnings Statement. Orders and related documentation help establish the new figure and the timeline.
Does BAH stop when I leave active duty?
Yes. BAH is an allowance for active-duty members who do not live in government-owned housing, and it ends when that status changes. If you plan to separate, build a budget around your remaining income sources, such as civilian employment, retirement pay, or disability compensation, and document them before applying.
Do I need a down payment if I use BAH to qualify?
VA loans typically offer a 0% down payment option, so the down payment is usually not the obstacle. What matters more is your full monthly payment, including property taxes, homeowners insurance, and HOA dues (when applicable), plus your other debts. A larger down payment can lower that monthly figure, but it does not replace the residual income review.
Missed the last post? Can I Get a VA Loan If I'm Changing Jobs? For more on VA home loans.