HOA Fees Do Not Disqualify You From a VA Loan But They Do Change Your Qualifying Numbers
The Line Item That Surprises VA Buyers Who Did Not Budget for It
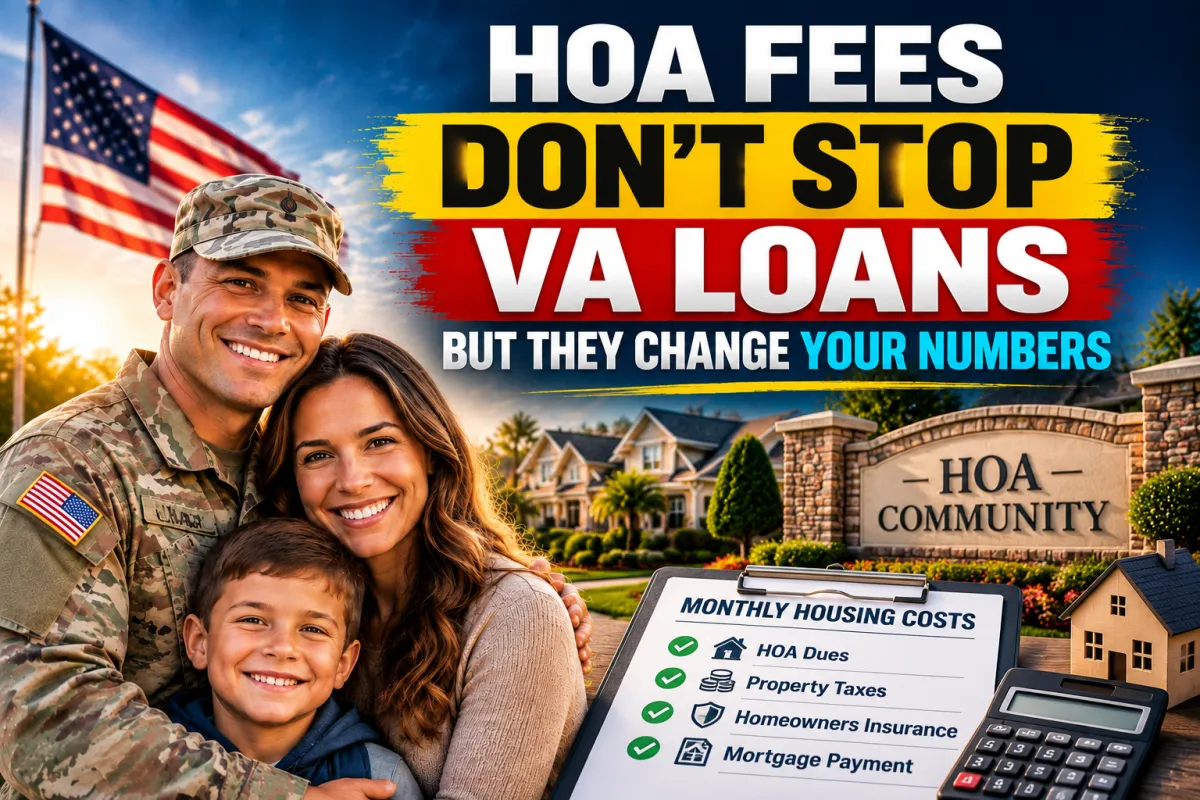
HOA fees will not stop a veteran from using their VA home loan benefit. But they do change the math and buyers who discover that after closing or late in the loan process are in a worse position than buyers who knew it from day one. Travis Egan builds the number in from the start rather than letting it show up as a surprise.
How HOA Fees Factor Into VA Loan Qualification
When a lender calculates what a veteran qualifies for the monthly housing payment is not just principal and interest. It includes property taxes, homeowners insurance, and HOA dues when the property is part of a homeowners association. All of those recurring costs count toward the monthly housing obligation that is evaluated against the veteran's income.
The VA loan program has its own residual income requirement in addition to the standard debt-to-income ratio calculation. Residual income is the amount of money left over after all major monthly obligations are paid. HOA dues reduce that residual income number and depending on the size of the fee and the veteran's income picture that reduction can be meaningful.
A veteran who qualifies comfortably for a property with no HOA may qualify for a lower purchase price on a property with significant HOA dues if those dues push the monthly housing cost above what the income supports. The VA benefit does not change. The specific purchase price that is achievable with that benefit adjusts based on the full monthly cost picture.
Why Some HOA Fees Around Clarksville Surprise Buyers
Some neighborhoods in the Clarksville and Fort Campbell area carry HOA fees that buyers did not anticipate when they started their home search. A property that looks affordable based on the listed price and an estimated mortgage payment can look different once monthly dues are added to the calculation. For buyers operating close to the top of their budget that difference matters.
Knowing the HOA amount before falling in love with a specific neighborhood or property is part of shopping intelligently rather than reactively.
How Travis Egan Handles This
The HOA fee goes into the calculation from day one. Not at the loan estimate stage. Not after a purchase contract is signed. From the very beginning of the qualification conversation so that the numbers veterans are working with reflect the actual monthly cost of the homes they are considering rather than an incomplete estimate that has to be corrected later.
Got questions about how HOA fees or any other monthly cost affects your VA loan qualification? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
ConsumerFinancialProtectionBureau.gov
MilitaryOneSource.mil
MortgageNewsDaily.com
Investopedia.com