Thinking About Applying for a VA Loan and Here Is Exactly What to Gather Before You Start
The Document List That Eliminates Last-Minute Scrambling
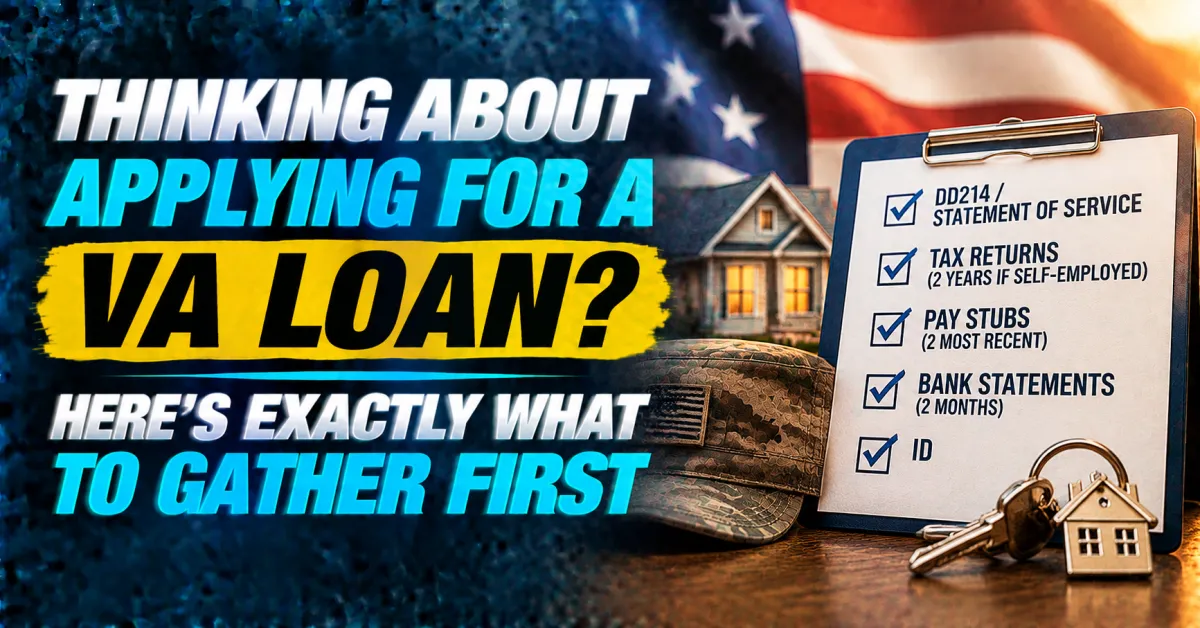
One of the most stressful parts of the mortgage process for veterans and service members is discovering mid-application that documents are missing or need to be tracked down urgently. Travis Egan sends every client a simple checklist before the process begins so nobody is scrambling when it actually matters. Here is the starting point for a VA loan application.
What You Need to Pull Together First
Your DD214 or statement of service is the foundational document that establishes your eligibility for the VA home loan benefit. If you are still active duty your statement of service from your commanding officer serves this purpose. If you have separated from service your DD214 is what the lender needs to confirm your qualifying service history.
Two years of tax returns apply specifically to self-employed borrowers and those with complex income situations. W-2 employees with straightforward income may not need full tax returns at the initial stage but having them ready removes a potential delay if underwriting requests them.
Your two most recent pay stubs document current income for employed borrowers. This is one of the documents that needs to be current so pulling these at the moment you are ready to apply rather than weeks in advance keeps everything accurate.
Two months of bank statements verify the funds you have available for closing costs and any required reserves. The statements should show your name, account number, and all transactions for the period covered.
Your government-issued ID rounds out the starting package.
Why Starting With a Complete Package Matters
Getting these items organized before the application begins rather than in response to individual lender requests keeps the process moving smoothly from the start. Missing documents create delays at the worst possible moments, particularly when a closing date is involved and every day counts. Veterans with PCS timelines or deployment considerations especially cannot afford documentation delays that push their closing past a hard deadline.
Travis Egan sends a simple checklist to every client so the starting point is clear and nothing gets missed. Got questions about your VA loan or what documents apply to your specific situation? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com