VA Loan Occupancy Rules: How Long Do You Have to Live There?
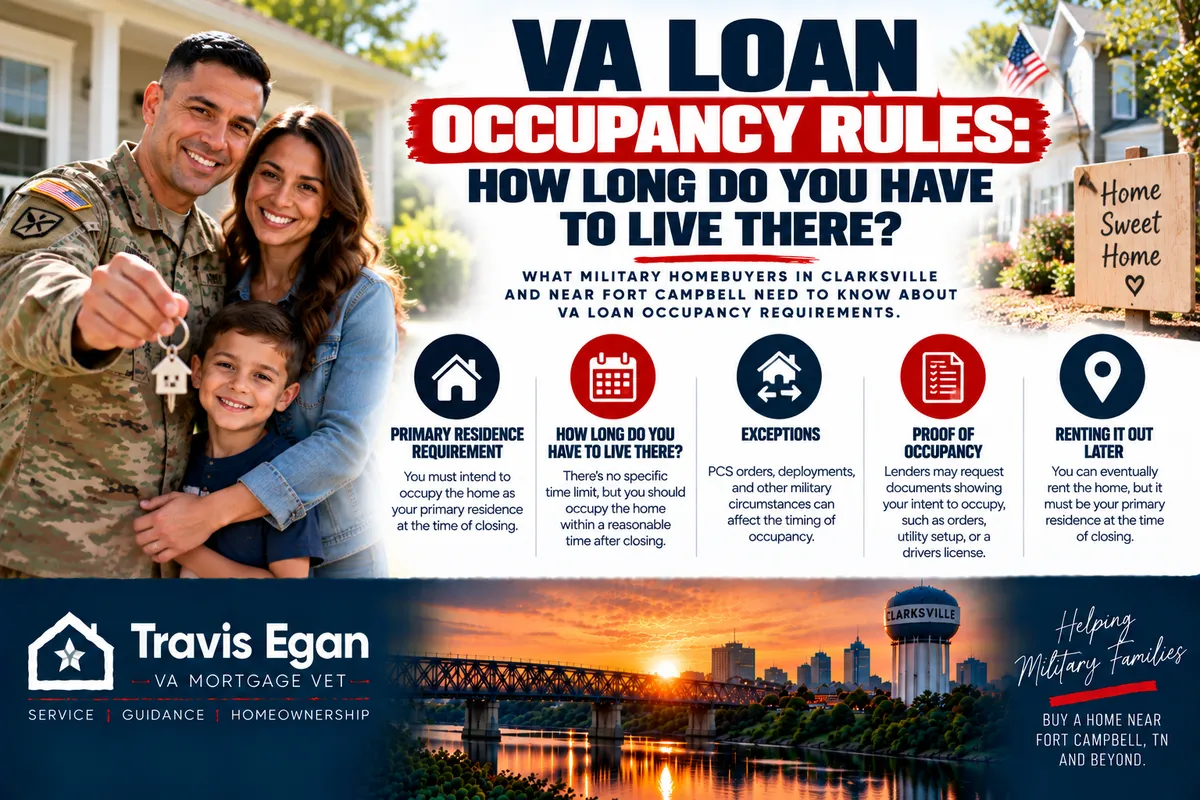
Most VA buyers hear one number early in the process: sixty days. You'll see it in lender emails, conversations with real estate agents, and the stack of paperwork you sign at closing. That number matters, but it is not the entire rule. The VA is really asking whether you intend to make the property your primary residence and whether you follow through within a reasonable time. Understanding how those two ideas work together clears up a lot of confusion, particularly when your timeline depends on orders rather than preference.
This matters even more around an installation like Fort Campbell, where PCS moves, deployments, and family decisions rarely line up neatly with a closing date. Here is what the occupancy requirement actually says, where the exceptions live, and how to keep your loan on solid ground.
What the VA Means by Owner Occupancy
The VA loan guaranty exists to help veterans and service members buy a home to live in. It wasn't designed to fund rental portfolios, which is why the occupancy requirement exists.
A fundamental requirement of the program is that the borrower must certify their intent to personally occupy the property as their home. That certification underpins everything that follows. It is not a promise that nothing in your life will ever change after closing. It is a statement of what you plan to do at the moment you sign.
From there, the VA expects you to actually move in. The VA Lender's Handbook requires occupancy within a reasonable time after closing, and the VA generally considers 60 days reasonable. Put another way, VA loan rules require you to move into the home within 60 days of closing to confirm the property is your primary residence.
How Long Do You Have to Move In?
Sixty days is the working benchmark, not an ironclad countdown clock. The VA uses the term "reasonable time," and 60 days is how the agency typically interprets it. If your situation is straightforward, plan on being in the home within roughly two months of signing.
Things get interesting when your situation isn't straightforward. The VA recognizes that military life and homeownership don't always align, and it builds flexibility into the timeline for the situations below.
Situation | What the VA looks at |
|---|---|
Standard purchase, buyer ready to move | Occupancy within a reasonable time, generally about 60 days |
PCS orders affecting your timeline | Recognized exception to the standard timeline |
New construction not yet finished | Recognized exception to the standard timeline |
Employment change | Recognized exception to the standard timeline |
Deployed service member | VA makes an exception for deployed service members |
Is There a 12-Month Occupancy Rule?
Search for VA occupancy rules, and you will run into the phrase "12-month rule." It is one of the most misunderstood ideas in the VA loan world.
No simple federal 12-month law physically forces you to stay in the home for exactly one year. The core VA issue is owner-occupancy intent, not a universal rule requiring twelve months of residency. You generally sign documents at closing stating that you intend to occupy the home as your primary residence, and that intent at the time of closing is what matters most.
Life can change after closing. If something legitimate changes, an early move-out may still be acceptable. The VA's main standard is that the property wasn't bought under false pretenses as a disguised investment. A job transfer, new orders, or a change in family circumstances tells a very different story than buying a house you never intended to live in.
Who Can Satisfy the Occupancy Requirement
You do not always have to be the person sleeping in the house every night. Under VA rules, your home must be your primary residence, but a spouse or dependent can count as the occupant.
This detail matters enormously for active-duty borrowers. If you receive orders that send you to another duty station while your family remains in the home you purchased, the property can still function as the family's primary residence. The same logic applies when a dependent occupies the home while the veteran's work takes them elsewhere for a period of time.
The key is that the home is genuinely a residence for you or your immediate family, not a property that sits empty while someone else pays rent.
Exceptions That Give You More Time
Three scenarios come up again and again when borrowers need flexibility on the move-in timeline. Each one is a recognized reason for a delay, and each one is easier to navigate when you document it before closing rather than after.
PCS Orders
Permanent change-of-station orders are the most common reason a VA buyer cannot move in right away. Orders can arrive after you close, or they can shift your report date in a way that makes the 60-day window unrealistic. PCS orders are a recognized exception, meaning a delay tied to your orders isn't treated the same as simply choosing to stay away.
Construction Delays
When you are building a home, the move-in date depends on the builder, the weather, and the pace of inspections. The VA recognizes construction as a valid reason occupancy takes longer than the standard window. Keep records of the construction timeline so the reason for the delay is clear if anyone asks later.
Employment Changes
Employment changes fall into the same category. A new job, a transfer, or a shift in where your work is located can reasonably push back the date you occupy the property. The VA treats this as an exception, not a violation, as long as the change is real and documented.
What Is Intermittent Occupancy?
Intermittent occupancy is a term underwriters use for a specific pattern: a long commute plus a second residence. The borrower spends part of the week at the property and part of it somewhere else, often near a job site or military installation.
VA treats active duty and civilian jobs differently in these situations. Underwriters need the full picture: where you work, where your family lives, how often you are at the home, and why the arrangement exists. Underwriters evaluate a borrower who commutes long distances for a civilian job differently than an active-duty service member stationed away from the property. The documentation matters as much as the explanation.
Why Underwriters Ask So Many Questions
Occupancy questions can feel intrusive, especially when you have already provided orders, pay stubs, and a certificate of eligibility. The reason is simple: the VA guaranty protects the lender, and that protection depends on the loan being for a primary residence.
If something in your file suggests the home might not be your primary residence, an underwriter must resolve it before the loan can move forward. That could mean a written explanation of your living situation, a copy of your orders, or details about who will occupy the property and when. Answering early and completely speeds up underwriting. Waiting until the last week before closing to raise a complication turns a small question into a delay.
If your circumstances are unusual, say so up front. A loan officer who knows about a pending deployment or a delayed build at the start of the process can structure the file correctly from the beginning.
Buying Near Fort Campbell: Why the Timeline Matters Locally
Clarksville and the surrounding Fort Campbell area see a steady stream of VA purchases tied to PCS orders, and the occupancy question comes up in nearly every one of them. Buyers arrive with a report date, a family still finishing a school year, or a spouse staying behind to sell an old house. Those are ordinary realities, not red flags, but they do need to be handled correctly.
Travis Egan is a Marine Corps veteran and VA mortgage specialist who works with active-duty service members, veterans, and military families in the Clarksville, Tennessee, and Fort Campbell, Kentucky, area. Through his affiliation with Loan Factory, he offers VA purchase and refinance options with $0 down, along with PCS relocation support and fast approval timelines for buyers working against a report date. If your move-in timeline is complicated by orders or construction, that conversation belongs at the beginning of the process, not the end.
Keeping Your VA Loan in Good Standing
The simplest way to think about VA loan occupancy requirements is this: intend to live there, actually move in within a reasonable time, and tell the truth about your situation. The 60-day benchmark covers most buyers. The exceptions cover the rest.
If something changes after you close, do not assume you have broken a rule. Communicate with your servicer, keep your documentation, and remember that the VA's real concern is whether you purchased the home as a residence or an investment in disguise. Buyers who keep that distinction clear rarely run into trouble. Buyers who treat a VA loan as a way into rental property usually do.
Before you close, confirm your specific timeline and any exceptions that apply to you with your lender and with the VA, since individual files can raise details that a general rule cannot address.
Frequently Asked Questions
How long do I have to move into a home I buy with a VA loan?
The VA Lender's Handbook requires occupancy within a reasonable time after closing, and the VA generally treats 60 days as reasonable. At closing, you certify your intent to occupy the property as your primary residence, so the expectation is that you move in and make it your home rather than leaving it vacant or renting it out to someone else.
Is there a 12-month rule for VA loans?
No simple federal law forces you to stay in the home for exactly twelve months. The core issue is owner-occupancy intent, and that intent at the time of closing matters most. If something legitimate changes after you close, you may still be able to move out early. The VA will not accept a purchase made under false pretenses as a disguised investment.
Can my spouse satisfy the VA occupancy requirement?
Yes. The home must be your primary residence, but a spouse or a dependent can count as the occupant. This matters for active duty buyers whose orders take them elsewhere while their family remains in the home. The property still serves as the family's primary residence, which is the standard the VA is applying.
What happens if I get PCS orders after closing?
PCS orders are a recognized exception to the standard occupancy timeline. The VA allows a reasonable delay when orders, construction, or an employment change affect your ability to move in on schedule, and it gives deployed service members special consideration. Keep copies of your orders and share them with your loan servicer so the reason for the delay is documented.
What is intermittent occupancy on a VA loan?
Intermittent occupancy generally describes a long commute plus a second residence. The VA treats active-duty and civilian employment differently in these situations, so underwriters closely review where you work, where your family lives, and how often you are actually at the property. If your life involves two locations, expect to explain it clearly before closing.
Missed the last post? Military Spouse VA Home Loan: Eligibility and How It Works. For more on VA home loans.