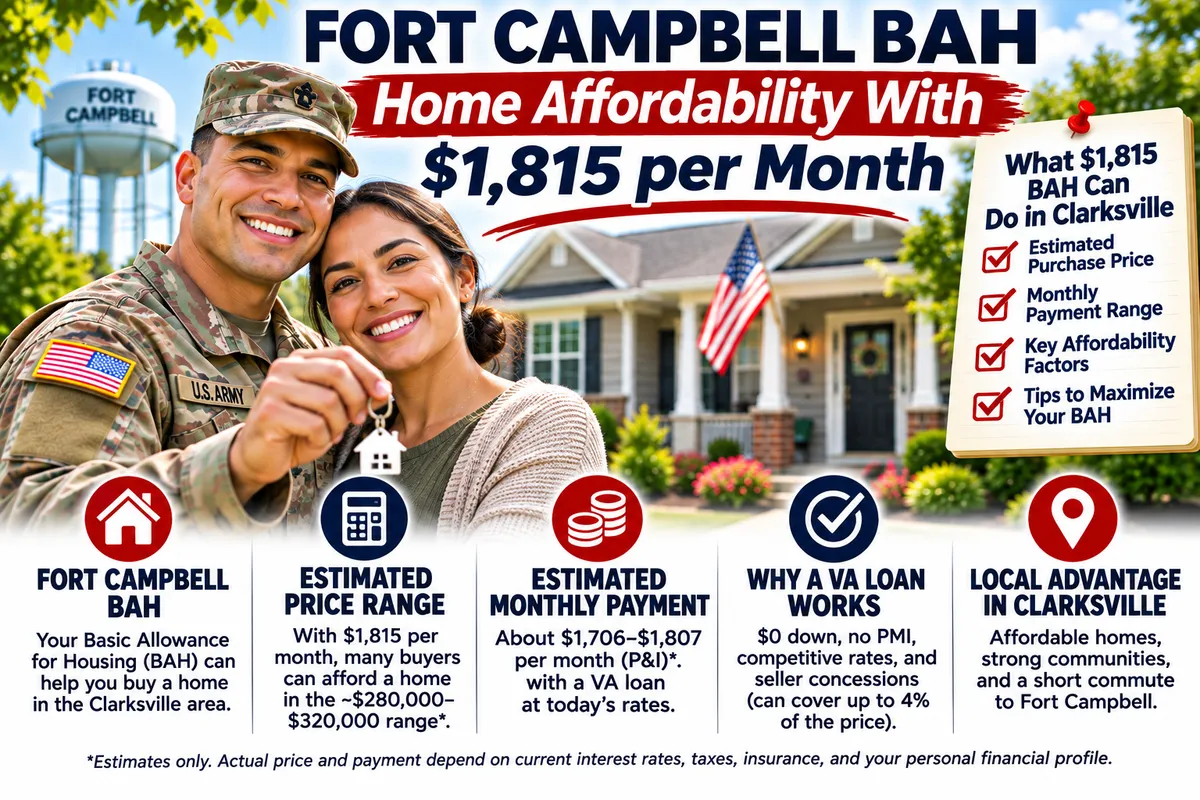
Fort Campbell BAH Home Affordability With $1,815 per Month
A $1,815 monthly BAH doesn't translate into a specific maximum home price. That allowance is tax-free income, and a VA lender can generally count it when building your qualifying military income. Your real purchasing power also depends on base pay, BAS, other qualifying income, monthly debts, the interest rate, property taxes, homeowners insurance, HOA dues, credit profile, household size, and VA residual income. Two families with the same $1,815 BAH can be approved for very different loan amounts.
Fort Campbell sits on the Kentucky-Tennessee state line, and many families assigned there end up living in Clarksville, Tennessee, which has no state income tax on wages and a growing housing market. That choice matters for affordability, because property taxes and insurance costs follow the location of the house, not the gate you drive through each morning.
How Much House Can I Afford With $1,815 BAH?
Fort Campbell BAH home affordability starts with a mindset shift: treat the allowance as part of your income, not as a mortgage payment limit. A lender does not look at $1,815 and hand you a price tag. It looks at your total qualifying income, subtracts the debts you already carry, applies VA underwriting standards, and then tells you the loan amount that fits.
That cuts both ways. Some service members qualify for a total housing payment above $1,815 because base pay and other qualifying income cover the rest. Others need to stay comfortably below $1,815 because a truck payment, credit cards, student loans, child care costs, or a larger household shrink the room available for a mortgage.
Here is the practical version. Your BAH covers housing. Your base pay covers everything else: groceries, utilities, insurance deductibles, savings, and the surprise expenses that come with homeownership. If the mortgage payment eats the entire allowance plus a chunk of base pay, the numbers may still get approved while the budget gets uncomfortable.
What $1,815 in BAH Looks Like at Different Purchase Prices
The table below uses a hypothetical 30-year fixed rate of 6.5%, shown only to demonstrate the math. It is not a current rate quote, and it is not an offer of specific terms. Property taxes are estimated at 0.80% of the purchase price per year, homeowners insurance at $150 per month, and HOA dues at zero. For simplicity, we assume a zero down payment and no VA funding fee added to the loan balance.
Assumptions Behind These Illustrative Numbers
Every assumption in that paragraph changes the answer. A higher interest rate increases principal and interest. A county with higher property taxes increases the escrow portion. A home with an HOA adds a monthly line item that lenders count in your total housing payment. If the VA funding fee is financed into the loan instead of paid at closing, the loan balance rises and so does the payment.
Purchase Price | Estimated Principal and Interest | Estimated Taxes and Insurance | Estimated Total Monthly Housing Payment |
|---|---|---|---|
$200,000 | $1,264 | $283 | $1,547 |
$225,000 | $1,422 | $300 | $1,722 |
$250,000 | $1,580 | $317 | $1,897 |
$275,000 | $1,738 | $333 | $2,071 |
$300,000 | $1,896 | $350 | $2,246 |
Reading the Table
At these assumptions, a $225,000 purchase lands just below the full $1,815 allowance. A $250,000 purchase runs about $82 above it. A $300,000 purchase runs roughly $431 above it, which means base pay would need to absorb that difference every month. None of those outcomes are automatically wrong or automatically smart. They show where the allowance stops covering the payment.
Actual payments will move based on interest rate, property location, taxes, insurance, funding-fee status, HOA dues, and other factors. Ask for a loan estimate built on a specific address rather than relying on a generic table.
Why You Should Not Shop for a Payment That Equals Exactly $1,815
Searching for a house whose mortgage payment exactly matches your BAH is a common shortcut, and it usually leads to one of two mistakes. The first is underestimating. A buyer caps the search at $1,815 when base pay could responsibly support more, then settles for a less expensive house than the budget allows. The second is overestimating, where a buyer forgets that taxes, insurance, and HOA dues sit on top of principal and interest.
BAH is income. It arrives in your paycheck whether your mortgage is $900 or $2,400, and it does not adjust based on what you buy. The question is not how to match the payment to the allowance. The question is how much total housing payment your full financial picture supports, and then how much of that you actually want to spend.
Does BAH Count as Income for a VA Loan?
Properly documented BAH can generally be included when calculating your qualifying military income. Lenders understand that housing allowances are a standard part of military compensation, and they are comfortable counting allowances that are documented and expected to continue.
Your Leave and Earnings Statement answers most of the questions. It shows the BAH you currently receive, your base pay, and other entitlements. A lender reviews it to verify the amount and stability of the allowance, then confirms the income is expected to keep flowing at the new duty station.
That last part is where PCS situations get specific. A lender wants to see the allowance that will apply to the property you are financing, not an allowance from a previous assignment that no longer exists.
Base Pay, BAS, and Other Military Compensation
A lender evaluates your complete qualifying income picture rather than looking at BAH in isolation. Base pay is the foundation and usually the largest single number on the application. Basic Allowance for Subsistence adds another non-taxable piece. Special pays, imminent danger pay, flight pay, and other documented entitlements can also count when they are stable and expected to continue.
This is why two E-5s with identical $1,815 BAH can receive different approval amounts. One may have several years of service with higher base pay and special assignment pay. The other may be earlier in their career, with lower base pay and no additional entitlements: same allowance, different income.
How Do Monthly Debts Change What I Can Afford?
Monthly obligations are the fastest way to change your purchasing power without changing your BAH by a single dollar. In a straightforward debt-to-income framework, every $100 of monthly debt reduces the housing payment you can support by roughly $100. A $1,000 monthly debt load can therefore erase about $1,000 of housing room, which translates into a meaningfully smaller loan amount at any given rate.
Borrower | Monthly Vehicle Debt | Other Monthly Debt | Approximate Reduction in Housing Room | Practical Result |
|---|---|---|---|---|
Borrower A | $0 | $0 | $0 | Full $1,815 BAH plus base pay available for housing |
Borrower B | $250 | $100 | About $350 | Can still qualify comfortably, with less room at higher price points |
Borrower C | $700 | $300 | About $1,000 | May need to shop well below the full allowance to stay within guidelines |
Borrower A and Borrower C receive the same $1,815 BAH and may have the same pay grade. Borrower C's $700 truck payment and $300 in other monthly debt create a completely different approval profile. Identical BAH does not produce identical VA loan approval amounts.
Payoff strategies matter here. Paying off a small credit card balance or selling a vehicle you no longer need can change your numbers before you ever talk to a lender. Run the scenario both ways and see what the difference looks like.
Debt-to-Income Ratio and Residual Income in Plain English
Debt-to-income ratio compares your total monthly obligations to your gross monthly income. Add up the proposed mortgage payment, taxes, insurance, HOA dues, car loans, credit cards, student loans, and any other installment debt, then divide by your qualifying monthly income. A lower number generally means more breathing room.
VA underwriting does not treat 41% as an absolute ceiling. VA places significant emphasis on residual income, which is the money left over after the mortgage, debts, taxes, and certain household expenses are accounted for. A borrower with a higher debt ratio but high residual income may be approved where another borrower with the same ratio is not.
Think of it this way. Debt-to-income measures how much you owe relative to what you earn. Residual income measures whether your family can actually live on what remains. VA cares about both, and household size affects the second.
Why Household Size Matters
VA residual income requirements vary by household size and region. A single service member supporting only themselves has a lower residual income threshold than a service member supporting a spouse and several children. The difference is not a penalty. It reflects the reality that a family of five spends more on food, clothing, and everyday expenses than a single person does.
As a result, two service members with similar income and debt can receive different qualification outcomes because their households look different. If you are planning to grow your family, factor that into the budget conversation before you commit to a payment.
What Happens to My BAH When I PCS to Fort Campbell?
BAH can change when you change duty stations. Rates are set by duty station, pay grade, and dependent status, and they are updated annually, so the allowance you received at your last base may not match what Fort Campbell pays for your situation. Confirm the current rate for your pay grade and dependent status before you build a budget around it.
Mortgage qualification should use the income expected to continue at the new location, not the allowance from your previous assignment. A lender will want documentation that reflects your actual situation at Fort Campbell, which is why a PCS timeline and a clear picture of your new entitlements matter during pre-approval.
Local knowledge also helps. A home in one county may carry different taxes than a home a short drive away, and insurance costs vary by location and property type. Getting a payment estimate for a specific address is more useful than comparing sticker prices alone.
A Practical Way to Work Through Your Numbers
Pull your most recent Leave and Earnings Statement and identify base pay, BAH, BAS, and any special pays.
List every monthly debt with the payment amount, including vehicle loans, credit cards, student loans, and personal loans.
Confirm the Fort Campbell BAH rate for your pay grade and dependent status.
Get pre-approved so the numbers come from underwriting, not a guess.
Ask for payment estimates on specific addresses so taxes, insurance, and HOA dues are included.
Your $1,815 allowance is a strong starting point, and in many cases it covers most or all of a comfortable payment on a well-chosen home in the Fort Campbell area. The number that matters is the one that fits your full budget, not the one that happens to match your BAH.
Frequently Asked Questions
Can I use my BAH as income on a VA loan?
Yes, properly documented BAH can generally count as qualifying military income. Lenders verify it through your Leave and Earnings Statement and confirm the allowance is expected to continue. The allowance is non-taxable and treated as part of your overall compensation, not a separate housing stipend that limits your loan amount.
Does my whole BAH have to go toward the mortgage?
No. BAH is income, and it lands in your account like any other pay. You decide how much of it goes to housing. Some families put most of the allowance toward the mortgage, and some use a portion of base pay as well. Others buy below their allowance and redirect the difference toward savings or debt payoff.
Can I qualify for a payment higher than $1,815?
Possibly. Approval depends on total qualifying income, including base pay and other entitlements, minus your monthly debts and adjusted for household size and residual income. A service member with modest debt and a higher base pay may qualify above the allowance. A service member with significant debt may need to stay below it.
Will my BAH change when I PCS to Fort Campbell?
It can. BAH rates are set by duty station, pay grade, and dependent status, and they are updated annually. The allowance you received at your previous assignment may not match the Fort Campbell rate. Confirm your current rate before setting a housing budget, and use the expected allowance when you apply.
What costs besides principal and interest affect my payment?
Property taxes, homeowners insurance, HOA dues, and any financed VA funding fee all affect the total monthly payment. Taxes and insurance are collected in escrow and can shift when the property location changes. A home that looks affordable on principal and interest alone may feel different once the full payment is calculated.
Missed the last post? VA Loan No PMI: Monthly Savings for Clarksville Homeowners. For more on VA home loans.