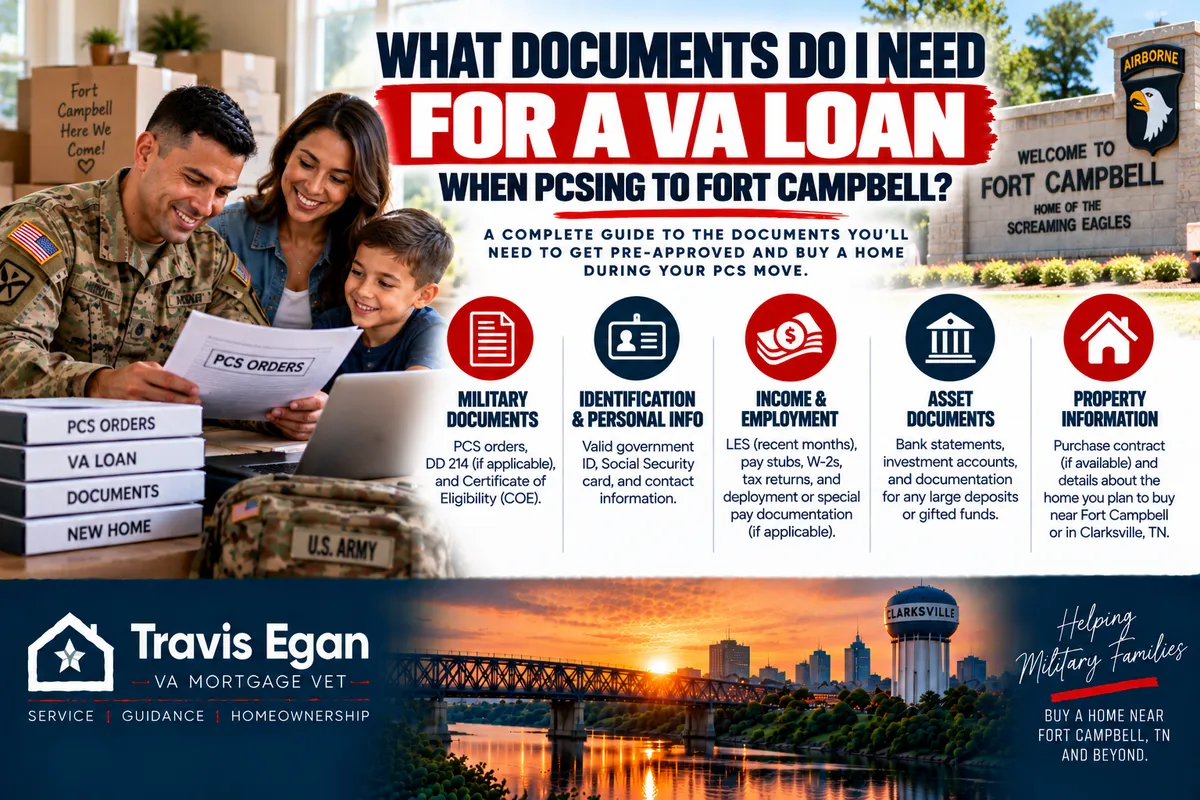
What Documents Do I Need for a VA Loan When PCSing to Fort Campbell?
PCS orders are usually among the first documents a lender requests when a service member buys a home with a VA loan, and they are often required for the file. A complete copy of your official PCS orders and your most recent Leave and Earnings Statement are typically the primary documents a VA lender needs when you move under orders. PCS orders are only one piece of the paperwork, though. Your file still needs income, asset, credit, and occupancy documentation before it can close.
Fort Campbell PCS VA Loan Documents: What Do You Need?
When you apply for a VA loan while PCSing to Fort Campbell, the lender is building a story about you. That story explains where you are going, when you are going, how much you will earn when you get there, and why the home you are buying will be your primary residence. PCS orders cover part of that; the rest comes from standard mortgage paperwork.
The exact list can vary by lender, loan program, and your individual situation, so treat this as a starting point rather than a final list. A loan officer will tell you what your specific file needs.
A complete copy of your official PCS orders
Your most recent Leave and Earnings Statement (LES)
Recent pay statements
W-2s when applicable
Bank statements and asset documentation
Government-issued identification
Your Certificate of Eligibility (COE) for the VA loan benefit
Documentation of current debts and obligations
Homeowners insurance information for the property
Moving and housing documents, including shipping paperwork
Spouse employment or remote work documentation, if spouse income is used to qualify
Any amended orders or changes to your report date
Leslie-style checklists help, but the underlying logic matters more. Lenders want to confirm you are who you say you are, that you can repay the loan, and that the move is real and documented.
Why PCS Orders Matter in a VA Loan File
PCS orders do a few jobs at once. They confirm your move is official, identify your new duty station, and give the lender a framework for your occupancy plan and expected compensation at the new location. Without them, a lender may struggle to connect your current situation to the home you want to buy.
Relocation and Duty Station
Your orders show that Fort Campbell is your new assignment. That matters because a VA purchase loan is tied to a primary residence, and a move under orders explains why you are buying in the Clarksville, Tennessee, or Fort Campbell, Kentucky, area rather than staying where you are.
Occupancy Plan
Orders also support your intent to live in the home. They show your move timeline and the location you are reporting to, which helps the lender understand when you plan to occupy the property and how that aligns with closing.
Expected BAH at the New Location
Your Basic Allowance for Housing can change when you PCS. A lender may need to verify the BAH you expect at Fort Campbell rather than relying only on the amount you receive at your current duty station. Orders help anchor that conversation because they confirm where you are going. Your LES and any updated pay information help confirm what you will actually receive.
BAH Documentation: Why Your New Duty Station Matters
BAH is location-based, so moving to a new duty station can change how much you receive. That change can affect how much house you can afford and how the lender calculates your qualifying income.
Why Current BAH May Not Be Enough
If the lender only looks at your current LES, it may be using a number that will not apply after you report to Fort Campbell. Expect to provide orders and updated pay documentation so the file reflects the allowance tied to your new station. If your BAH is expected to decrease, the lender needs to know that early, not after underwriting has already run the numbers.
What to Expect
Ask your loan officer how they want BAH documented before you start house hunting. Some files may need an updated LES, and some may need a letter or additional verification. Requirements vary, so confirm with your lender instead of assuming your current amount will carry over untouched.
Can You Buy a Home Before You Arrive at Fort Campbell?
Buying before your report date is common for military members. A VA loan can still work when you are moving under PCS orders, and you can begin the mortgage process before you physically move.
The lender still needs to document the move, your occupancy plan, your income, and how closing will be handled if you are not yet in the area. That may mean signing remotely, working with a real estate agent who is familiar with VA loans and military moves, and keeping your loan officer informed about your travel and reporting dates. Buying before arrival is as much a scheduling challenge as a financial one.
Amended or Delayed PCS Orders
Orders change. Report dates shift, duty stations get adjusted, and relocation timelines move. When that happens, tell your lender immediately.
A different report date, duty station, or relocation timeline can affect underwriting, BAH calculations, occupancy, and closing. A file that was built around one set of orders may need to be rebuilt around another. The earlier your loan officer knows, the more options you have for keeping the timeline on track.
Spouse Income After a PCS Move
PCS moves disrupt military spouse employment more than almost anything else in the mortgage file. A spouse may transfer with an employer, work remotely, start a new job, or take time off during the move. Each situation is documented differently.
Remote Work
If a spouse works remotely and will keep the same employer after the move, the lender may want a letter from the employer or other documentation confirming the income will continue. Remote income isn't automatically treated the same as local income, so be ready to show the job continues regardless of location.
Employer Transfers
A transfer to a new location with the same employer is generally easier to document, but the lender still wants written confirmation. An employer letter can confirm the transfer, start date, and continued income.
New Jobs and Temporary Unemployment
If a spouse plans to find work after arriving, you usually can't use that future income to qualify before it exists. If a spouse is temporarily unemployed during the move, you must build the file without that income. In some cases, an offer letter with a confirmed start date may help, but whether it counts depends on the lender. Do not wait until the last minute to raise this with your loan officer.
Active-Duty Income Documentation
Military compensation is more layered than a single salary figure. Your file may include base pay, BAH, Basic Allowance for Subsistence, special pay, and other compensation. The lender must determine which portions are documented, which are expected to continue, and how each counts toward qualifying.
That is why your LES matters so much. It shows the components of your pay rather than one lump sum. When a PCS changes your BAH, or when special pay is tied to a specific assignment, the lender needs to understand what carries forward. Anything that will not continue should not be treated as stable income.
Occupancy Requirements and VA Purchase Loans
VA purchase loans are intended for a primary residence. Your PCS orders can help explain why you are moving to the Fort Campbell area and support your stated intent to occupy the home.
Orders alone do not automatically satisfy every occupancy requirement, so avoid treating them as a substitute for the rest of the file. The VA itself does not publish a rule on how long you must live in a home, but your lender may have its own requirements, so read your loan documents and ask questions. Occupancy is reviewed as part of the whole picture.
What If I Do Not Have Final PCS Orders Yet?
Some buyers start the mortgage process with projected orders or early relocation information. Exact lender requirements vary, and some files can move forward with what is available while final orders are pending.
Starting the conversation early is almost always better than waiting for every document to be final. A loan officer can tell you what can be reviewed now, what has to wait, and how to sequence your house hunt around the paperwork. Waiting until you have the orders in hand can compress your timeline when you have the least flexibility.
A Practical Timeline for Providing Documents
Timing matters as much as the documents themselves. This sequence keeps the file moving without forcing you to scramble.
Stage | What to Provide |
|---|---|
Before house hunting | Talk to a VA loan specialist, confirm your COE, and get a clear list of what your file will need. |
When you apply for the loan | PCS orders or projected orders, most recent LES, pay statements, bank statements, identification, and debt information |
After receiving final orders | A complete copy of the final orders and any updated pay documentation showing BAH for the new duty station |
During underwriting | Anything the underwriter requests, including spouse employment letters, homeowners insurance information, and explanations for changes |
Before closing | Final verifications, updated statements if requested, and confirmation that nothing in your situation has changed |
Common Documentation Mistakes
Most delays in a PCS mortgage file come from small gaps rather than big problems. These are the ones that keep coming up.
Submitting an outdated LES instead of the most recent one
Not disclosing amended orders or a new report date
Assuming your current BAH amount will remain unchanged at Fort Campbell
Waiting too long to document spouse employment or a remote work arrangement
Failing to tell the lender about a change in duty station or relocation timeline
Letting bank statements or pay documents expire before underwriting reviews them
Each of these is fixable. The problem is timing. A document that arrives a week late can push a closing date past the point where it works for your move.
Working With a Fort Campbell VA Loan Specialist
Travis Egan is a VA mortgage specialist and Marine Corps veteran based in Clarksville, Tennessee, working with military families connected to Fort Campbell through Loan Factory. He helps active-duty service members and veterans assemble the documentation a VA loan file needs, including PCS orders, LES statements, BAH verification, and spouse income paperwork, so the process moves at mission speed instead of stalling on missing documents.
Frequently Asked Questions
Are PCS orders required for a VA loan?
A complete copy of your official PCS orders is commonly listed among the primary documents a VA lender needs when you are moving under orders, along with your most recent Leave and Earnings Statement. Exact requirements can vary by lender and situation, so confirm what your specific file needs. Orders are one part of a larger document set.
Can I start my VA loan before my PCS orders are final?
Some buyers start with projected orders or early relocation information while final orders are pending. Lender requirements differ, so the practical answer is to talk with a loan officer early. Starting the conversation sooner gives you more room to sequence house hunting, underwriting, and closing around your report date.
Will my BAH change when I PCS to Fort Campbell?
BAH is tied to location, so a PCS can change the amount you receive. Your lender may need to verify the BAH expected at your new duty station rather than relying only on your current amount. Provide your orders and updated pay documentation so the file reflects the allowance that applies after you report.
How do I document spouse income after a PCS move?
It depends on the situation. Remote workers may need an employer letter confirming the job continues. A spouse transferring with the same employer may need written confirmation of the transfer. Future income from a job that has not started yet usually cannot be used to qualify, so raise any employment changes with your loan officer early.
Missed the last post? Can I Get a VA Loan If I'm Changing Jobs? For more on VA home loans.