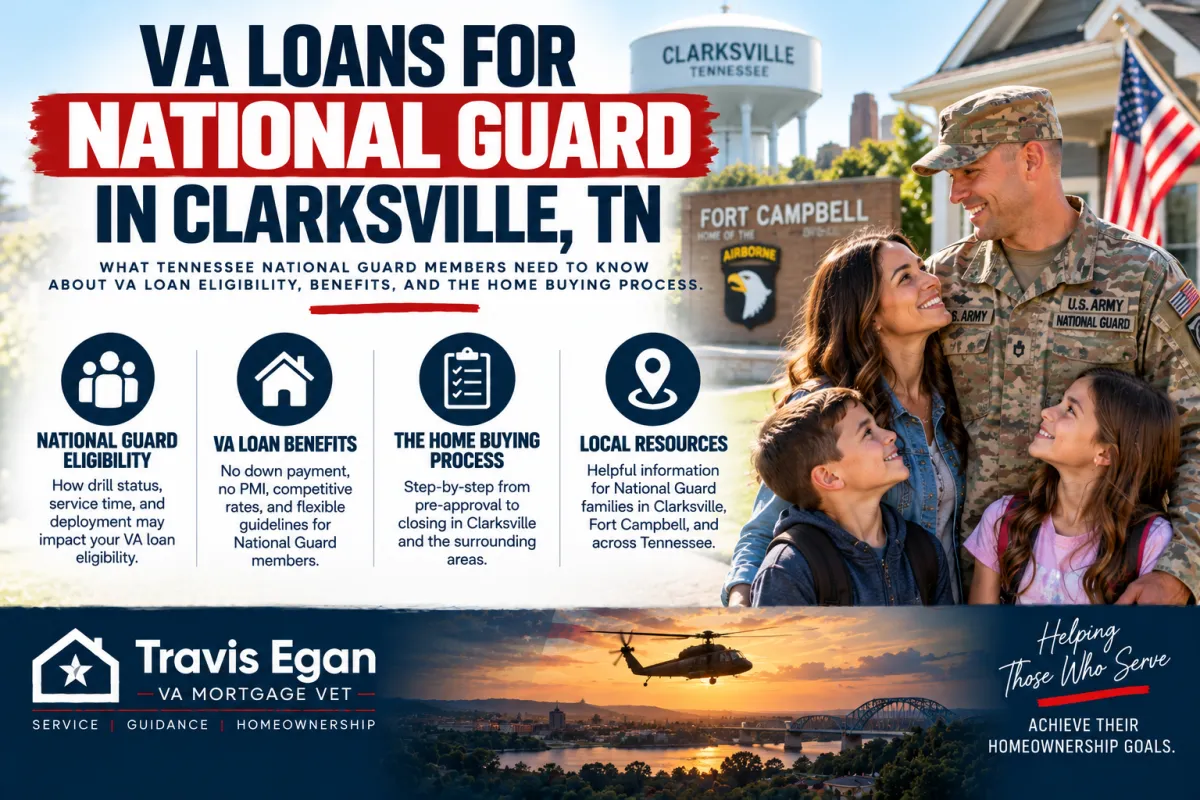
VA Loans for National Guard in Clarksville TN
Yes. National Guard and Reserve members can use a VA loan in Clarksville, Tennessee, but the eligibility rules that apply to them differ from the rules that apply to someone who served full-time on active duty. That difference trips up many people around Fort Campbell, especially Guardsmen who have drilled for years without deploying or who were activated for a stretch shorter than they remember.
The VA loan is an earned benefit tied to military service. It isn't available to everyone who puts on a uniform, and it isn't limited to full-time active duty either. Guard and Reserve members sit in the middle of that conversation, and the two tests that decide their eligibility are simple once you know what they are.
Who Qualifies for a VA Loan in Clarksville
The VA purchase loan has a defined pool of eligible borrowers. If you fall into one of these groups, you can pursue a VA loan, and if you are in the National Guard or Reserve, the question becomes which set of service requirements applies to you.
Active-duty service members
Veterans
Qualifying National Guard and Reserve members
Certain eligible surviving spouses
Guard and Reserve service is grouped with the other categories in the VA program, which surprises people who assume the benefit is reserved for those who served on active duty only. The benefit follows your service record, not your current duty status, so a drilling Guardsman and a recently separated active-duty soldier may both qualify for the same loan program.
The Two Paths Guard and Reserve Members Use to Qualify
There are two ways a National Guard or Reserve member establishes eligibility. You only need to satisfy one. This is the part of the process where most confusion happens, so it helps to look at each path separately.
Path One: Six Years of Service
A Guard or Reserve member who has served six years meets the service requirement. That can be six years of drilling weekends and annual training, without any deployment, without any active-duty orders, and without ever leaving the state. Time in service is the qualifying factor here, and it accumulates the same way regardless of whether your unit was busy or quiet during those years.
If you are approaching the six-year mark and have started thinking about buying a home near Fort Campbell, that timeline is worth tracking. Knowing where you stand on your service anniversary can shape when you start shopping.
Path Two: Activation for at Least 90 Days
The second path is activation for at least 90 days. A Guard or Reserve member who was activated for 90 days or more meets the service requirement through that activation, even without six years in uniform. This path tends to apply to members who were called up early in their careers or who spent significant time on active orders.
Both the length of the activation and the type of orders matter to how your service is documented, so it is worth confirming how your specific record reads before you assume you do or do not qualify. If you have any questions about your activation history, confirm it with the VA or your unit's administrative office rather than relying on memory or a secondhand answer from someone in your shop.
What Guard and Reserve Members Actually Get With a VA Loan
Once eligibility is established, the loan works the same way it does for any other eligible borrower. The value of the program is in the terms, and those terms are the reason Guard members who qualify often stop looking at other loan types.
A $0 down payment option on a VA purchase loan
No monthly mortgage insurance
Flexible guidelines compared with some conventional programs
Competitive rates relative to many non-VA alternatives
The no-down-payment feature matters more in a market like Clarksville than it might elsewhere. If you are stationed at or near Fort Campbell and facing a move, keeping cash available for the transition instead of sinking it into a down payment changes what the next few months look like for your family.
VA Construction Loans in Tennessee
Buying an existing home is not the only option. VA construction loans are designed for eligible veterans, active-duty service members, qualifying National Guard and Reserve members, and certain surviving spouses. These programs let you finance the construction of a primary residence with little to no upfront cost, which opens up the possibility of building rather than buying.
Tennessee has plenty of room to build, whether you are looking in the Clarksville area or a surrounding community. If building a custom home is on your list, ask specifically about construction financing when you start the conversation. The eligibility groundwork is the same, but the process and timeline aren't identical to a standard purchase.
Why This Question Comes Up So Often Near Fort Campbell
Clarksville sits next to one of the largest military installations in the country, and the local population includes active-duty soldiers, veterans, retirees, Guard members, and Reservists all living within a short drive of each other. When neighbors and coworkers compare notes about how they bought their homes, the details get mixed together fast. Someone hears that a friend used a VA loan with nothing down, assumes the same rules apply to their own Guard service, and skips the step of actually checking their eligibility.
The reverse happens too. Guard members assume the benefit is only for active-duty soldiers and never ask, so they shop for a conventional loan and a down payment requirement they may not have needed. A short conversation up front settles the question in minutes.
How to Start the Process as a Guard or Reserve Member
The order of operations is not complicated, but doing it in the right sequence saves time and avoids wasted effort.
Confirm your eligibility status based on your service record, using either the six-year standard or the 90-day activation standard.
Gather your service documentation so your history can be verified without back-and-forth delays.
Talk to a lender who works with VA loans regularly and understands Guard and Reserve service records specifically.
Get pre-approved so you know your price range before you tour homes.
Work with a real estate agent who is comfortable with VA transactions and familiar with the local market.
Active-duty households dealing with a PCS move may need to compress that timeline, and the same basic steps still apply. Getting pre-approved early gives you room to move quickly if orders land on short notice.

Common Misconceptions That Cost Guard Members Time
Misconception: Part-Time Service Does Not Count
Drilling status does not disqualify you. A Guard or Reserve member who has served six years meets the requirement regardless of whether that service was full-time. Part-time is not a disqualifier in the VA program; it is simply a different route to the same benefit.
Misconception: You Need a Deployment to Qualify
Activation for at least 90 days is one qualifying path, but it is not the only one. A Guard member with six years of service and no deployment history can still qualify. The two paths exist side by side, and you need only one.
Misconception: Guard and Reserve Loans Have Worse Terms
Once you are eligible, you are eligible. The loan terms available to you come from the VA program itself, not the service category that got you there. There is no separate, lesser version of the benefit for Guard and Reserve borrowers.
If anything about your record is unclear, say so out loud rather than guessing. Eligibility questions get resolved with documentation, not assumptions, and it is far easier to sort out before you are under contract. For borrowers in the Clarksville area, call 931-208-6280 to review your service history and see where you stand before you start house hunting.
Frequently Asked Questions
Can I get a VA loan if I am in the National Guard?
Yes, if you meet one of the two service requirements. Guard and Reserve members qualify after six years of service, or after being activated for at least 90 days. Both paths lead to the same VA loan program, with the same $0 down payment option and no monthly mortgage insurance.
How long do I need to be in the National Guard for a VA loan?
Six years of service satisfies the requirement without any activation. If you were activated for at least 90 days, that activation can satisfy the requirement instead, even if you have not reached six years yet. You only need to meet one of the two standards.
Do National Guard members have to make a down payment on a VA loan?
VA loans offer a $0 down payment option and no monthly mortgage insurance. That combination is part of why the benefit is so valuable for military families. Confirm the details of your specific scenario with your lender before you write an offer.
Does Reserve service count the same as National Guard service?
Guard and Reserve members are treated together in the VA program. The same six-year and 90-day activation standards apply to both. Whether your service was in the National Guard or the Reserve doesn't change which requirements you need to meet or what the loan offers once you qualify.
Can I use a VA construction loan if I am in the Guard or Reserve?
VA construction loans are designed for eligible veterans, active-duty service members, qualifying National Guard and Reserve members, and certain surviving spouses. If you qualify for a VA purchase loan, ask specifically about construction financing, because building a home differs from buying an existing one in Clarksville.
Missed the last post? VA Loan Portability and PCS: Can You Keep Your Rate? For more on VA home loans.