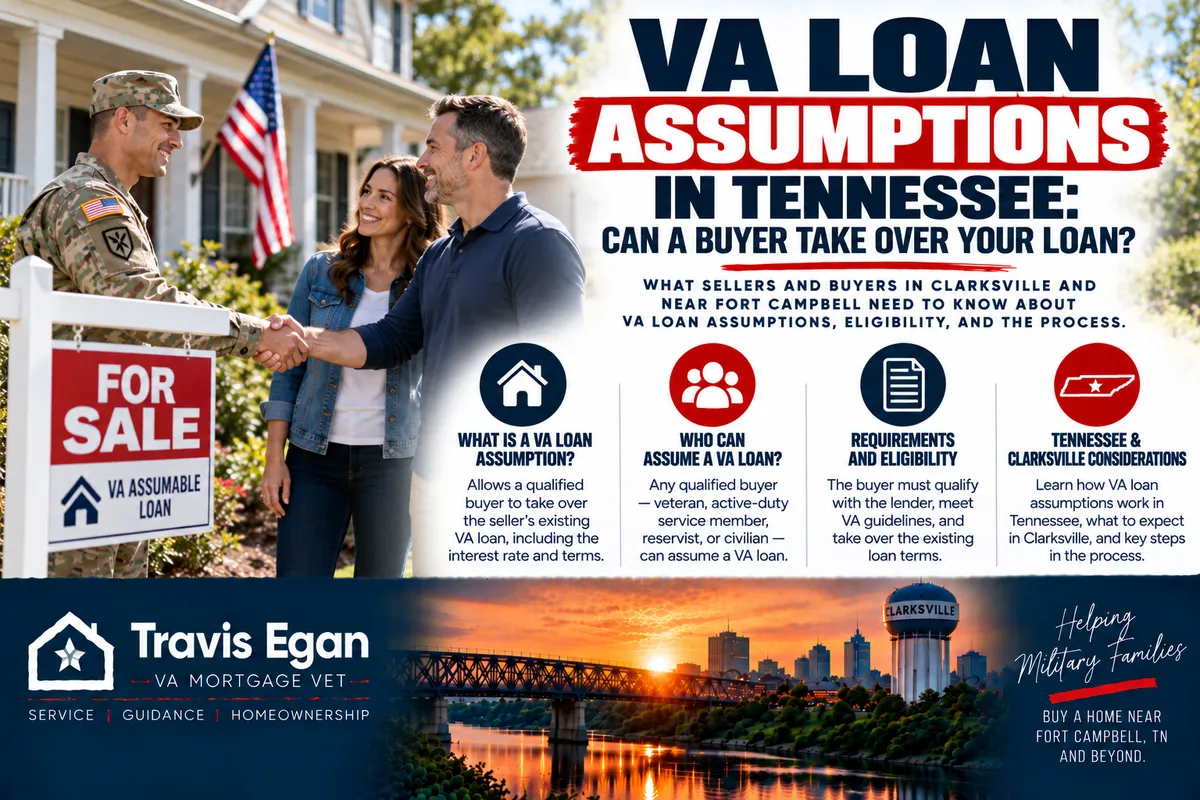
VA Loan Assumptions in Tennessee: Can a Buyer Take Over Your Loan?
A VA loan assumption lets a buyer take over the seller's existing VA mortgage and keep paying it, rather than the seller paying it off at closing and the buyer starting a new one. Around Fort Campbell and across Middle Tennessee, that question comes up whenever rates shift, because an assumable loan may carry a rate from an earlier purchase. Here is how the mechanics work in Tennessee, what buyers have to prove, and what veterans give up when someone else takes over the note.
What a VA Loan Assumption Actually Is
An assumption is a transfer of an existing mortgage from one borrower to another. The loan itself does not change. Same note, same balance, same remaining term, same interest rate. What changes is who is legally responsible for the monthly payment.
VA loans are generally assumable, and so are FHA loans. Conventional loans vary by lender and program, so a conventional mortgage may or may not allow it. That makes the assumption question especially relevant for sellers whose homes were financed with a VA loan, because the feature comes with the product rather than being negotiated case by case.
Who Is Allowed to Assume a VA Loan in Tennessee?
A VA loan can be assumed by any buyer the servicer approves, not only by another veteran. Non-veterans do assume VA loans. The gate is not the buyer's military status. The gate is the lender's qualification standards, which apply to an assumption just as they would to a brand new mortgage.
In practical terms, a Tennessee buyer who has never served can take over a VA loan if the servicer's credit and income review clears. FHA and VA loans are generally assumable, but buyers must meet the lender's qualification standards, and that requirement does not disappear just because the loan already exists.
The veteran-to-veteran scenario gets extra attention because the VA has been explicit about it. In early 2024, the VA warned mortgage lenders and servicers that they must process veteran-to-veteran loan assumptions in accordance with regulations or face penalties. That warning matters if you are the seller and the buyer is another service member, because the process is not optional for the servicer.
The Seller's Side: VA Entitlement and What It Costs You
When someone assumes your VA loan, you do not simply walk away clean. The veteran loses that amount of VA loan entitlement while the loan remains outstanding. That matters if you plan to buy again with a VA loan, because your remaining entitlement affects how much you can borrow without a down payment.
Whether you are released from liability on the old loan is a separate question from entitlement, and it is one you should confirm in writing with the servicer and with the VA before closing. Do not assume that an approved assumption removes your name from the obligation.
If another veteran assumes the loan, the entitlement picture can work differently than if a non-veteran assumes it. Ask specifically which situation applies to your file, and get the answer in writing rather than relying on a verbal explanation at the closing table.
What Buyers Have to Prove to the Servicer
The servicer reviews the whole financial picture, not a single number. That review typically includes payment history, income stability, monthly debts, debt-to-income ratio, VA residual income, and the proposed housing payment. The Department of Veterans Affairs does not set one universal minimum credit score for every VA loan. Lenders apply their own credit standards and must evaluate the borrower's complete financial picture.
That is why an assumption isn't a shortcut to qualification. A buyer with a thin file may still qualify if compensating factors offset it, but the servicer makes the final decision. A Tennessee buyer hoping to take over a loan should expect to document income and debts the same way a new borrower would.
VA Residual Income Minimums in Tennessee
Tennessee sits in VA's South region. For loans of $80,000 or more, the residual income minimums include these figures.
Household size | Minimum residual income (loans of $80,000 or more) |
|---|---|
One person | $441 |
Family of four | $1,003 |
Loans under that threshold are measured against different figures, and other household sizes have their own minimums. Residual income is what remains after the housing payment and other obligations are subtracted, and it is a separate test from the debt-to-income ratio. Buyers should verify the current numbers with the servicer rather than relying on any single published table.
How a Tennessee Assumption Runs, Step by Step
Confirm the loan is assumable and find out who currently services it. Sellers do not always know, and the answer determines everything that follows.
Contact the servicer's assumption department early. The servicer runs the process, not the real estate agent and not the closing attorney.
Have the buyer complete the servicer's application and credit review. Expect income, asset, and debt documentation.
Put the assumption in the purchase contract, including how any gap between the existing loan balance and the agreed price will be handled. If the balance is lower than the price, the difference has to come from somewhere, so decide that before the contract is signed.
Close, then confirm the servicing transfer and your liability status in writing before you consider the matter finished.
Listing a Home With an Assumable VA Loan
The most effective thing a seller can do is make sure the assumption is advertised in the listing. Many buyers, and even some agents, never think to ask. Have your agent include it in the listing remarks so buyers searching the Fort Campbell area can see it while scrolling. Suppose the existing note carries a rate below what a new mortgage would cost today; that belongs in the marketing rather than buried in a disclosure packet. A buyer comparing two similar homes will often weigh the financing as heavily as the floor plan.
Assumptions Are Less Common Than You Might Expect
Assumable loans are less common than traditional mortgages in the Nashville and Middle Tennessee market, even though FHA and VA loans are generally assumable. Many sellers never mention the feature. Many buyers never ask about it. For a military family near Fort Campbell, that gap is an opening.
If you are selling a home with a VA loan and plan to buy again, the assumption conversation belongs in your planning from day one, not at the closing table. Your next purchase depends on how much entitlement you still have, and that depends on what happens with the loan you are leaving behind.
Questions to Ask Before You Agree
Will I be released from liability on this loan, and can you confirm that in writing?
How much of my VA entitlement stays tied up while the loan remains outstanding?
How does the outcome change if the buyer is a veteran versus a non-veteran?
What documentation does the servicer require from the buyer, and who coordinates that review?
How will any gap between the loan balance and the purchase price be covered?
What is the servicer's current process, and what milestones should both sides expect?
An assumption is not a shortcut around qualification, and it is not a clean exit for the seller. It transfers an existing obligation that must satisfy the servicer, protect the buyer's financing, and be understood by the veteran whose entitlement is on the line. In Tennessee, that starts with one call to the servicer and one honest conversation about the veteran's next steps.
Frequently Asked Questions
Can a non-veteran assume a VA loan in Tennessee?
Yes. A VA loan can be assumed by any buyer the servicer approves, including someone who has never served. The buyer still has to clear the lender's credit and income review, just like a new borrower. The larger consequence lands on the seller, who loses that amount of VA entitlement while the loan stays outstanding.
Does the seller lose VA entitlement when the loan is assumed?
The veteran loses that amount of VA loan entitlement while the assumed loan remains outstanding. If you plan to use a VA loan again, that reduced entitlement can limit your options on the next purchase. Ask the servicer and the VA to confirm in writing how much entitlement is tied up and what it would take to restore it.
How is an assumption different from a new VA loan?
With a new VA loan, the buyer's entitlement backs a fresh mortgage, and the seller's loan is paid off at closing. With an assumption, the existing note stays in place and only the borrower changes. The buyer is reviewed by the servicer rather than underwritten for a brand new loan, and the seller's entitlement stays connected to the loan.
What income standards apply to a VA assumption in Tennessee?
The servicer reviews payment history, income stability, monthly debts, debt-to-income ratio, residual income, and the proposed housing payment. The VA does not set one universal minimum credit score, so the lender's own standards govern. In Tennessee, which falls in VA's South region, residual income minimums for loans of $80,000 or more include $441 for a one-person household and $1,003 for a family of four.
Missed the last post? VA Loan Self-Employed Income in Clarksville: Rules That Differ. For more on VA home loans.