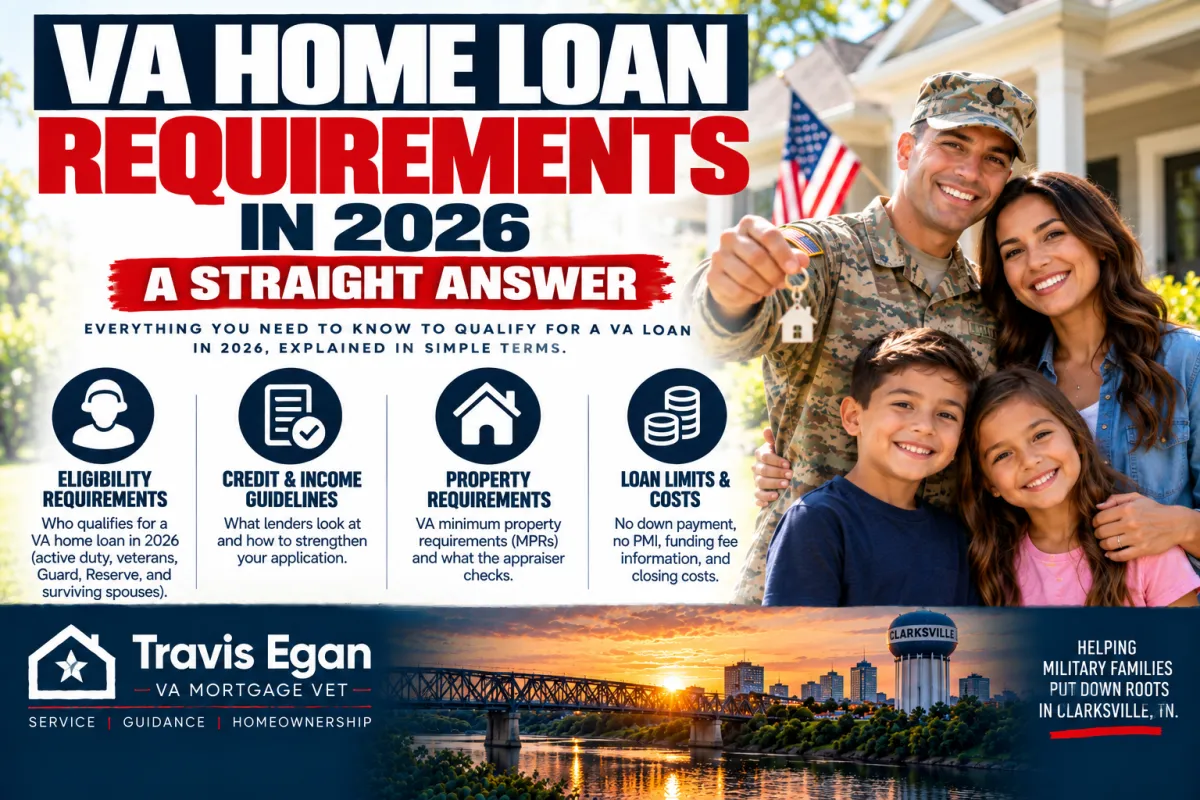
VA Home Loan Requirements in 2026: A Straight Answer
Ask ten people what it takes to get a VA home loan, and you will get ten different answers, most of them half right. The confusion is not because the rules are complicated. It is because three separate sets of rules get blended together: the ones the Department of Veterans Affairs sets, the ones your lender sets, and the ones that apply to the house itself.
Separate those three and the checklist becomes short. You prove you served, you satisfy your lender on credit and income, and you agree to live in the home. Everything else is detail.
The Three Buckets of VA Loan Requirements
According to the VA, getting financing for a VA-backed home loan means meeting credit, income, and occupancy requirements from both the VA and your lender. That sentence is the whole framework. The VA handles who is eligible and how the home is used. Your lender handles whether the loan makes financial sense.
Requirement area | Who sets the rule | What it covers |
|---|---|---|
Eligibility | VA | Your service history and duty status |
Credit and income | Your lender | Minimum credit score, ability-to-repay standards, documentation |
Occupancy | VA and your lender | Moving into the home within 60 days of closing |
Property condition | VA appraisal | Whether the home supports the loan and meets VA expectations |
Requirement One: Prove Your Service History With a Certificate of Eligibility
VA loan eligibility is based on your service history and duty status. There are many ways a homebuyer can qualify for this benefit, and you show a lender that you qualify with a Certificate of Eligibility, usually called a COE. The VA describes the COE as the document that shows your lender you meet the minimum active-duty service requirements.
You can request a COE through the VA. Most lenders can also pull it for you, which saves a step. Either way, it is the first document in the file, and nothing else moves until it is in place.
Who typically qualifies based on service
Veterans who served at least 181 days of continuous active duty during peacetime and were not dishonorably discharged.
National Guard members with at least 90 days of active service, including at least 30 consecutive days under Title 32 authority.
Active-duty service members and others whose service history and duty status meet the VA's minimum active-duty service requirements.
The VA also offers a VA direct loan, known as the Native American Direct Loan, alongside the VA-backed loan most buyers use. Both start with the same eligibility question: does your service record qualify you?
Credit Score: The Minimum Comes From Your Lender, Not the VA
This is the single most misunderstood part of the process. The VA does not require a minimum credit score. Your lender does. The VA's own buyer's guide is clear: you must meet your lender's standards for credit, income, and any other requirements the lender sets to approve a loan, and the VA itself does not impose a credit score floor.
In practice, that means two buyers with identical service records can get different answers from two different lenders. As one example, Veterans United typically requires a minimum credit score of 620 to qualify for a VA loan, and borrowers also need to meet ability-to-repay guidelines. Other lenders set their own numbers. If one lender turns you down on credit, that is a lender decision, not a VA decision, and it is worth a second call.
Income and Ability to Repay
There is no VA-published income figure you must hit. Instead, your lender runs an ability-to-repay analysis: can you cover this mortgage payment along with your existing obligations, based on documented income and the debts already on your credit report.
The documentation supporting that analysis comes from the lender, not the VA. The VA buyer's guide separates required loan documents into lender-required and VA-required documents, which is a useful distinction when gathering paperwork. Ask your loan officer for the lender list early so you are not chasing items the week of closing.
Occupancy: You Have to Live in the House
A VA-backed loan is for a primary residence, and the occupancy rule has teeth. The service member or veteran is expected to move into the property within 60 days of closing. The home must become your primary residence within that window.
Exceptions do exist for deployed service members and other specific circumstances. If a deployment, a dependent situation, or a temporary duty assignment complicates your timeline, raise it before closing, not after. Occupancy exceptions are handled case by case, and the answer depends on your orders and your lender's process.
Property Requirements and the VA Appraisal
The house has to pass its own review. A VA appraisal is part of the process, and it looks at both value and whether the property supports the loan. The VA buyer's guide also describes the VA escape clause, which gives a buyer a path out if the appraisal comes in below the purchase price.
This is a good reason to keep the appraisal conversation early with your real estate agent. If a property has condition issues a seller will not address, you want to know before you are deep into a contract, not during the final week.
The Funding Fee
For many borrowers, VA loan requirements in 2026 include paying an upfront funding fee. That fee is part of the program's cost structure, not a lender add-on, and it is typically financed or paid at closing, depending on how the loan is structured.
Not every borrower pays it, and how it applies depends on your individual situation. Before you build a budget, confirm the current fee structure and whether any exemption applies to you directly with your lender or through the VA. Anyone quoting you a number without asking about your service history is guessing.
Additional VA Loan Options That Follow the Same Rules
The purchase loan gets the attention, but the VA buyer's guide lists several other options that share the same eligibility foundation:
Energy Efficient Mortgage, for energy-related improvements
Alteration and Repair loan
Construction loan
Farm Residence loan
Loan assumption, where a buyer takes over an existing VA loan
If your plan involves building, repairing, or assuming a loan rather than a straight purchase, ask specifically about that program's requirements. The service-history piece stays the same. The property and paperwork pieces change.
How to Prepare Before You Apply
Confirm your eligibility and pull your Certificate of Eligibility.
Ask your lender for its minimum credit score and its required document list, in writing.
Talk through your occupancy timeline, especially if a deployment is on the calendar.
Ask how the funding fee applies to your specific service history.
Keep your financial picture steady while the loan is in process.
That is the entire preparation list. Everything else is execution, and execution is where a loan officer who works with military families every week earns their keep.
The Straight Answer
For 2026, the requirements for a VA home loan are: qualifying service history proven by a Certificate of Eligibility, meeting your lender's credit and income standards, using the home as your primary residence within 60 days of closing, and buying a property that passes the VA appraisal. The funding fee applies to many borrowers, and you should confirm it for your situation.
Notice what is not on the list. No VA credit score requirement, no VA income threshold, and no single lender standard applies to everyone. That flexibility is a feature. It also means the answer to "do I qualify" comes from a lender who will actually review your file, not a general rule someone repeats online.
Frequently Asked Questions
Does the VA require a minimum credit score?
No. The VA does not set a minimum credit score for a VA-backed loan. Your lender sets its own minimum, and those minimums vary from company to company. As an example, Veterans United typically requires a score of 620. If one lender denies you based on credit, another lender's standards may produce a different outcome, so it is worth asking directly.
How long do I have to move into the home after closing?
You're expected to move into the property within 60 days of closing, and the home must serve as your primary residence. Exceptions exist for situations like deployments. If your orders or family situation make that timeline unrealistic, tell your lender before closing so they can review the scenario properly.
What is a Certificate of Eligibility and how do I get one?
A Certificate of Eligibility, or COE, shows your lender that you meet the VA's minimum active-duty service requirements. You can request one from the VA, and many lenders will pull it for you during the application. It is based on your service history and duty status, so have your discharge paperwork handy.
Do National Guard members qualify for a VA loan?
Eligibility now includes National Guard members with at least 90 days of active service, including at least 30 consecutive days under Title 32 authority. Veterans who served at least 181 days of continuous peacetime active duty without a dishonorable discharge may also apply. Because eligibility rules have been updated, confirm your specific service record with the VA or your lender.
Do I have to pay the VA funding fee?
Many borrowers pay an upfront funding fee with a VA loan, and it applies to many purchases. Some borrowers don't pay it, depending on their circumstances. Rather than assume either way, ask your lender to confirm how the fee applies to your file, or check the current guidance directly through the VA.
Missed the last post? VA Loan Credit Score Requirements in 2026 for Clarksville Borrowers. For more on VA home loans.