Refinancing a VA Loan Does Not Mean Starting Over and Here Is the Streamlined Option Veterans Should Know
Refinancing a VA Loan Does Not Mean Starting Over and Here Is the Streamlined Option Veterans Should Know
The Myth That Is Keeping Veterans From a Lower Rate They Could Already Have
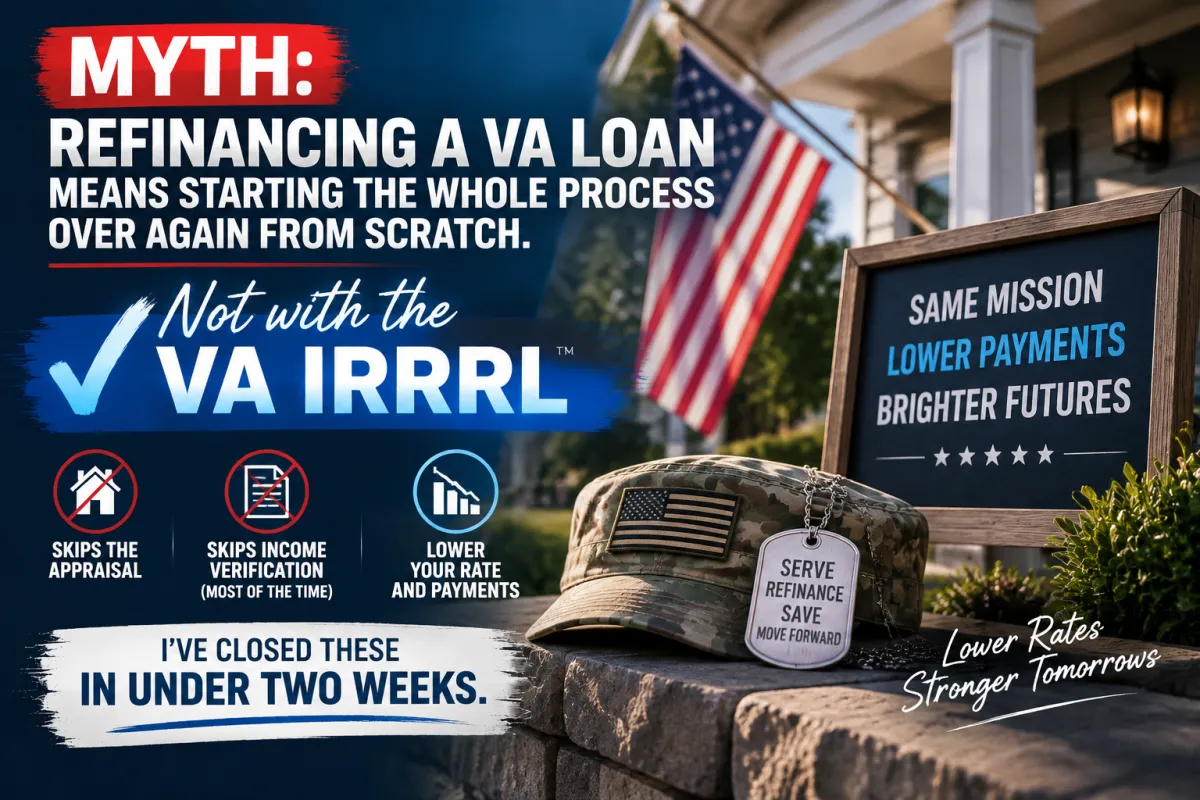
Refinancing a VA loan means starting the whole process over again from scratch. That is the belief that stops a lot of veterans from even asking the question. And for the standard refinance process it has some truth to it. But for VA-to-VA refinancing there is a completely different option that most veterans have never heard explained clearly.
What the VA IRRRL Actually Is
The VA Interest Rate Reduction Refinance Loan exists for one purpose. Lowering your rate and your payment on an existing VA loan. That is it. The program is not designed to pull cash out, restructure the loan term significantly, or accomplish anything beyond getting a veteran into a lower rate than they currently have.
Because the purpose is that narrow the process reflects it. No appraisal in most cases. No income verification in most cases. The documentation burden that makes a full refinance feel like repeating the original purchase process largely does not exist here.
Travis Egan has closed these in under two weeks. That is not typical of a standard refinance. It is typical of a program specifically engineered to remove friction from the process of helping veterans lower their rate.
Who This Is For
If your current VA loan carries a rate that is meaningfully higher than what is available in the market right now the IRRRL may be the fastest and simplest refinance you ever do. You are not going through underwriting of your income. You are not going through an appraisal of the property. You are demonstrating that you currently have a VA loan and that the refinance will produce a lower rate and a lower payment.
The eligibility requirements are specific and worth confirming for your individual situation. But for veterans who are sitting in a higher rate environment and have not looked at this option the conversation is worth having before another month passes at a rate that could already be lower.
What to Do Right Now
If your rate is higher than what is out there right now this might be the fastest paperwork you ever sign. Got questions about whether the VA IRRRL makes sense for your specific situation? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com