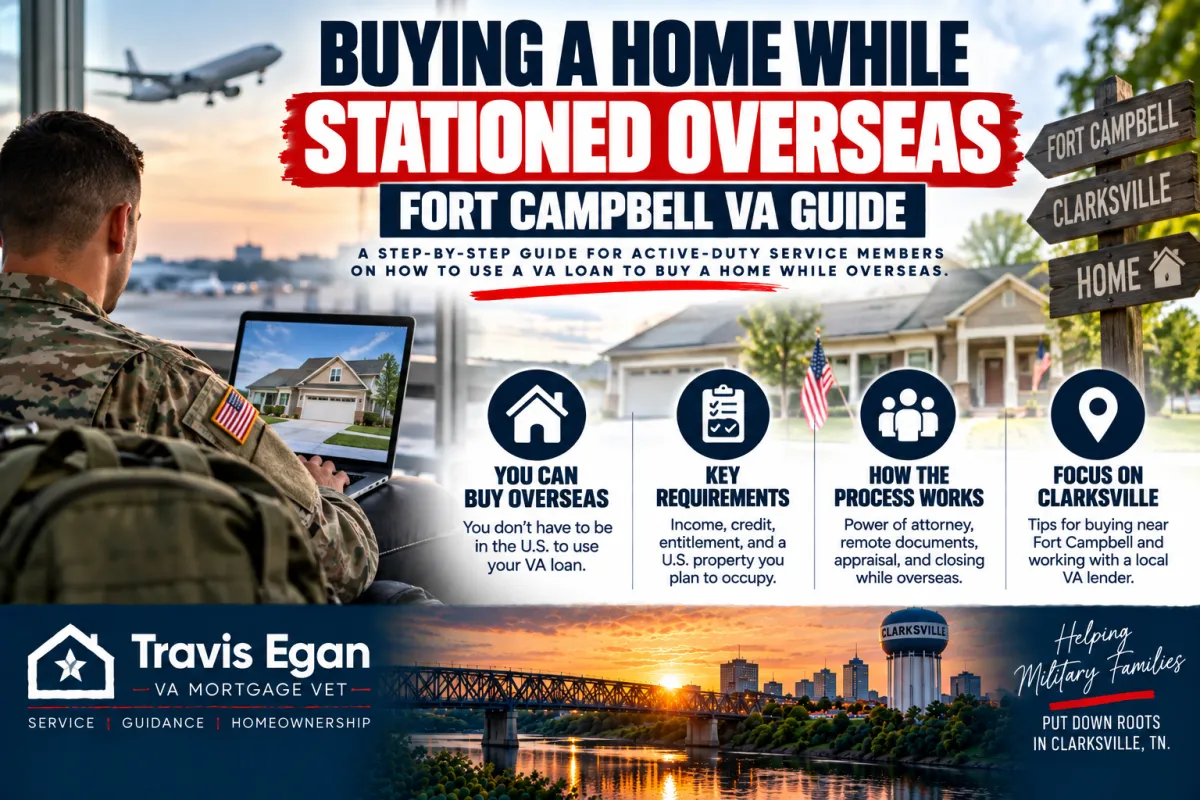
Buying a Home While Stationed Overseas: Fort Campbell VA Guide
Orders to an overseas duty station do not pause your plans to own a home. Fort Campbell soldiers on OCONUS assignments buy houses in the United States every month, and most use a VA loan to do it. The process looks different because you cannot stand in a kitchen or walk a fence line, but the transaction follows a familiar path once you build the right team.
Can You Buy a Home in the U.S. While Stationed Overseas?
Yes. Service members can use a VA loan to buy a home in the United States while stationed overseas, and many complete the purchase through a power of attorney. That answer applies to both a short deployment and a multi-year assignment far from Fort Campbell. The people who close these transactions are lenders, title companies, and other transaction professionals willing to work with a buyer who isn't physically present, so your first job is confirming everyone on your team has done it before.
One caution deserves repeating. Being overseas does not automatically waive VA loan requirements. A version of that claim circulates in military communities, and it is not accurate. The same requirements apply to your file, so your lender should spell out exactly what they expect before you write an offer, not after.
How a Power of Attorney Fits Into the Purchase
A power of attorney lets another person sign on your behalf when you cannot be at the closing table. You will need one to complete a homebuying process from overseas, because documents require signatures at moments when the time difference, your duty schedule, or your physical location makes it impossible for you to sign personally.
A power of attorney gives the person you name legal authority to act for you, and that authority should align precisely with the purchase you are making. Before you sign anything, confirm the details with a legal professional who understands military situations, then share the document with your lender and the title company so nobody discovers a gap on closing day. Getting this right early prevents the last-minute scramble that kills contracts.
What a Remote Home Search Actually Looks Like
Buying sight unseen is a repeatable process, not a leap of faith. It requires an agent who can run live video walkthroughs, so you see the house as it exists today instead of trusting listing photos taken at an unknown time. A live tour lets you ask the camera to swing toward the water heater, attic access, foundation line, or the street itself. Those are exactly the details a still photo hides.
Video is only one part of the arrangement. Plan on having:
Live video tours of every home you seriously consider
Written answers about anything you cannot see on camera
A clear understanding of who signs which document, and when
A lender, agent, and title company who all know you are remote
When those four things are in place, the distance between your duty station and a Clarksville address becomes a scheduling detail instead of a deal breaker.
What to Look for in a Real Estate Agent
Not every agent is set up to work with a client in a different time zone, and the difference shows up fast. Ask two direct questions before you hire anyone. First, how many sight-unseen transactions has the agent closed in the last year? Second, does the agent hold a Military Relocation Professional certification? Those answers separate an agent who markets to military families from one who has actually carried a remote buyer from offer to keys.
You also want someone who works on your schedule, not theirs. If you are calling from a location where the business day overlaps with the middle of your shift, an agent who can adapt is worth more than one with the biggest advertising budget.
Assembling Your Team Before You Start Shopping
The buying team does not change because you are overseas. What changes is how much coordination it takes to keep everyone moving in the same direction.
Your loan officer handles the VA loan file, keeps you informed of what is outstanding, and confirms what can be signed remotely.
Your real estate agent runs the search, handles video tours, and represents you in negotiations.
The title company manages the closing side and can tell you how documents will be executed with your power of attorney in place.
Because the research on these transactions points to lender, title, and agent approval as the deciding factor, confirm all three are comfortable with a remote closing before you fall in love with a house.
Why Clarksville and the Fort Campbell Area Make Sense for This
Soldiers stationed overseas routinely buy in the Clarksville, Tennessee area, and service members completing an OCONUS assignment can shop remotely, make an offer, and handle the paperwork without flying back first. That matters for Fort Campbell families because the base sits on the Tennessee and Kentucky line, and Clarksville is the community most military households already know, either from a previous assignment or from friends who are stationed there now.
Familiarity cuts down the risk of a long-distance purchase. When you already understand the neighborhoods, the commute to post, and the area's general layout, a live video tour fills in the gaps instead of introducing you to an entirely unknown market. If an overseas assignment has you thinking about where to land next, or where to land when you retire, a market you already know removes one variable from a decision that has plenty of them.
Timing Your Purchase Around Your PCS and Retirement Date
Two clocks usually run in parallel. The first is your PCS timeline, which controls when you will need a place and how long you have to shop. The second is your retirement date, which shapes how you think about the house in the first place. A soldier three years out from retirement may be buying the home they intend to stay in, while a soldier on a two-year overseas tour may be buying a rental-ready property or a house to grow into later.
Tell your lender which clock matters most to you and ask how the timeline affects your file. Also ask how occupancy expectations work when you are on orders far from the property, since your lender should answer that in writing rather than through group-chat rumors. Getting an answer early lets you plan around it instead of reacting.
Frequently Asked Questions
Can I buy a house in the U.S. while I am stationed overseas?
Yes. Service members can use a VA loan to purchase a home in the United States while stationed overseas, and this happens regularly. The transaction requires a lender, title company, and real estate agent willing to work with a remote buyer, plus a power of attorney so you can sign documents on your behalf when you cannot appear in person.
Do I need a power of attorney to buy a home from overseas?
You will need one to complete the homebuying process. A power of attorney gives another person legal authority to sign for you when your location or duty schedule prevents you from doing it yourself. Confirm the details with a legal professional, then share the document with your lender and title company before closing day arrives.
How do I tour a home I cannot visit in person?
Look for an agent who can do live video walkthroughs instead of sending photos. A live tour lets you direct the camera to specific areas, ask questions in real time, and see current conditions. Ask what else the agent will verify in person on your behalf so nothing important depends on a screen alone.
What should I ask an agent before hiring them for a sight-unseen purchase?
Ask how many sight-unseen transactions they have closed in the last year, and whether they hold a Military Relocation Professional certification. Those two questions reveal whether the agent has real experience serving remote military buyers. You should also confirm the agent can communicate on a schedule that works with your time zone and duty hours.
Does being stationed overseas waive any VA loan requirements?
No. It is a common misconception that an overseas assignment waives VA loan requirements, but that is not true. The same requirements apply to your file no matter where you are stationed. Ask your lender to explain, in writing, what each requirement means for your specific situation before you make an offer on a home.
The most useful step you can take right now is a conversation, not a house hunt. Talk to a lender who handles VA loans for Fort Campbell families, ask how the remote process works in detail, and line up your power of attorney before you start watching listings. Do that groundwork while you are still overseas, and the purchase becomes execution rather than improvisation.
Missed the last post? VA Loan Requirements by Credit Score: 580 vs. 620 vs. 700 in Clarksville. For more on VA home loans.