VA Loan Requirements by Credit Score: 580 vs. 620 vs. 700 in Clarksville
If you are stationed at Fort Campbell or settling into Clarksville after service, the credit score question comes up fast. Someone in your unit got approved at 580. Someone else was told they needed 620. A third person heard 700 opens doors. All three are right in their own way because the VA doesn't set a minimum credit score. Lenders do, and different lenders draw the line in different places.
What follows breaks down how 580, 620, and 700 tend to play out with real VA lenders, what else gets weighed alongside the number, and how to strengthen your file before you apply.
The VA Does Not Set a Minimum Credit Score. Your Lender Does.
This is what trips up many veterans and active-duty buyers. The VA guarantees a portion of the loan, but it doesn't publish a minimum credit score borrowers must meet. That means the requirement you actually face comes from the lender underwriting your file, not from the VA.
Lenders add their own rules on top of VA guidelines. Those extra rules are called overlays, and a credit score minimum is one of the most common. Because every lender writes its own overlays, the same borrower with the same score can be turned down at one shop and approved at another. Shopping lenders is not just about the rate. It is about which lender's credit box you fit inside.
What 580, 620, and 700 Actually Mean to a VA Lender
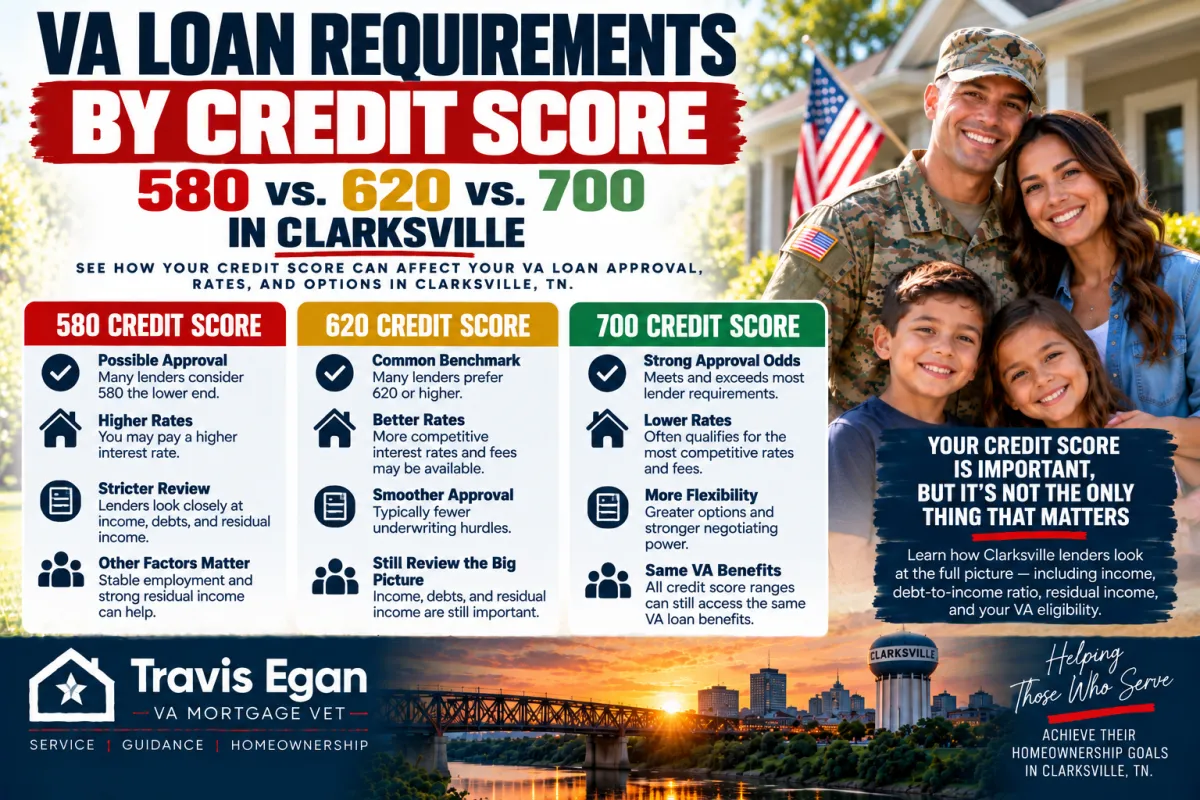
The three numbers most often mentioned in conversations about VA loan requirements are 580, 620, and 700. Here is the general pattern across the VA lending world.
Credit score | How VA lenders commonly treat it | What it usually means for you |
|---|---|---|
580 | Often described as the floor most lenders look for, though some go lower and some go higher | Approval is possible, but the lender pool is smaller, and the file gets more scrutiny |
620 | Widely cited as the preferred or typical threshold for VA loan applicants | The smoothest path among the three tiers, with more lenders willing to work with the file |
700 and above | Viewed as a strong, financially stable profile | More lender options and more room to negotiate on terms |
580: The Floor Most Lenders Talk About
A score of 580 keeps coming up as the minimum most lenders look for. It is not a VA rule. It is simply a common industry practice. Some lenders will approve below it, and others will not touch a file under it. If you land right at 580, expect the underwriter to read your full credit history rather than just glance at the score.
620: The Number Most Lenders Prefer
Ask around, and you will hear 620 most often. Lenders tend to see 620 or higher as a sign of financial stability and responsibility. One credit union, PenFed, lists 620 as its VA loan requirement, showing how the industry treats that number as a practical baseline.
Does that mean you are locked out at 619? No. Many lenders will still work with borrowers below 620, especially when the rest of the file is strong. A 620 is a preference in the market, not a wall.
700 and Above: Where Options Open Up
Once you cross into the 700s, the credit score stops being the obstacle. At that point, you are comparing lenders on service, speed, and terms rather than hunting for one willing to approve you. A higher credit score can help you secure better terms on your mortgage, though the exact difference depends on the lender and everything else in your file.
Below 580: Possible in Theory, Harder in Practice
The VA sets no minimum, so a 500 is theoretically possible. In practice, a score that low means the lender leans heavily on the last year of payment history and whatever explanation you can provide for past credit problems. Documentation, consistency, and compensating factors carry the file. It can be done, but it takes the right lender and a clear story.
Why Your Score Is Not the Whole Decision
A credit score is a snapshot, and underwriters know it. When a score sits on the lower end of the range, lenders dig into the details behind it. The last twelve months of payment history matter enormously, especially any mortgage or rent payments. A year of on-time payments after a rough patch tells a very different story than twelve months of missed ones.
Written explanations matter too. A medical emergency, a deployment-driven income gap, or a disputed account that got resolved all read differently than a pattern of overspending. Lenders want context. If something on your report needs explaining, explain it in writing rather than hoping nobody notices.
Lender Overlays: The Rule That Is Not a VA Rule
This is worth repeating because it changes how you should shop. The VA does not set a minimum credit score, so a denial is almost always a lender decision, not a VA decision. Requirements vary by lender, and some specialize in borrowers with dings on their credit, while others want clean files.
If one lender says no, that answer belongs to that lender. It does not travel to the next one. Working with a loan officer who understands VA underwriting and knows which lenders handle lower scores can save you weeks of dead ends.
Credit Score Questions Specific to Clarksville and Fort Campbell
Military buyers near Fort Campbell face a few wrinkles civilian buyers usually don't. PCS orders compress timelines. Households sometimes carry two addresses at once, and a spouse's income may be in transition. Rental history from on-base or off-base housing is often the strongest recent payment record a service member has.
None of that changes the credit score math, but it does change how the file is presented. Consistent rental payments, a stable employment picture after a transition, and a clear explanation of any deployment-related gaps all help a lender look past a single number. If you are relocating to the Clarksville area on orders, start the credit conversation before you pack, not after you arrive.

How to Improve Your Position Before You Apply
You do not need a perfect score to buy a home with a VA loan. You need the strongest version of the file you can put together. A few practical moves help.
Pull your credit reports before a lender does, and dispute anything that is inaccurate.
Keep every payment on time for the twelve months leading up to your application. Recent history carries the most weight.
Write a short, factual explanation for any collection, late payment, or derogatory item.
Avoid opening new credit accounts or taking on new debt while you are shopping.
Ask more than one VA lender what their own minimum score is, since it varies by lender.
Keep in mind that hundreds of different credit scoring models are in use, and scores range from 300 to 850. The score a lender pulls may not match the one you see in a consumer app. That is normal and not a sign that something is wrong.
Frequently Asked Questions
Does the VA require a 620 credit score?
No. The VA doesn't set a minimum credit score. The 620 figure comes from lenders, who commonly prefer that score or above when reviewing VA loan applicants. Some lenders approve borrowers with 580 or lower, and a few set higher minimums. The requirement you face depends entirely on the lender you choose.
Can I get a VA loan with a 580 credit score in Clarksville?
Often yes. A 580 is the floor most lenders look for, so it sits right at the edge of common approval ranges. At that score, lenders lean more on your recent payment history, your explanation of past credit issues, and the strength of your overall file. Working with a loan officer who knows which lenders handle 580 files makes a real difference.
Will a higher credit score get me a better VA loan rate?
A higher credit score can help you secure a better deal, and the gap shows up in how many lenders compete for your business. Specific terms vary by lender, loan type, and the rest of your financial picture. Your score is one input among several, so a strong file at 650 can outperform a thin file at 720.
What if my credit score is below 580?
It is possible in theory, since the VA sets no minimum. In practice, lenders focus on the last year of payment history and any explanation you can offer for past problems. Expect more documentation and a smaller list of lenders willing to work with you. Improving your score first is often the faster path to closing.
Which credit score do VA lenders actually use?
Lenders typically pull a mortgage-focused score from the major credit bureaus, which can differ from the free scores you see online. With hundreds of scoring models in circulation, small differences between your consumer score and the lender's number are normal. Ask your loan officer which score they will use before you apply.
Start with the number, but do not stop there. Your eligibility, your payment history, and the lender you choose carry just as much weight as the three digits on your report. If you are preparing to buy near Fort Campbell, the best move is a conversation about your specific file well before you start touring homes.
Missed the last post? VA Residual Income Explained for Fort Campbell Families. For more on VA home loans.