What Waiting for Rates to Drop Is Actually Costing You Every Single Month and Here Is the Math
The Cost of Waiting That Nobody Adds Up
Waiting for rates to drop feels like the cautious move. Travis Egan wants buyers who are in that holding pattern to actually run the numbers on what the wait is costing them before they decide how long they are willing to keep paying it.
What Every Month of Waiting Actually Produces
Every month you wait is another month of rent paid to a landlord. None of that payment builds equity. None of it comes back to you. None of it contributes to a down payment, a net worth statement, or a financial position that improves your options down the road. It is money that leaves your account and produces nothing lasting in return.
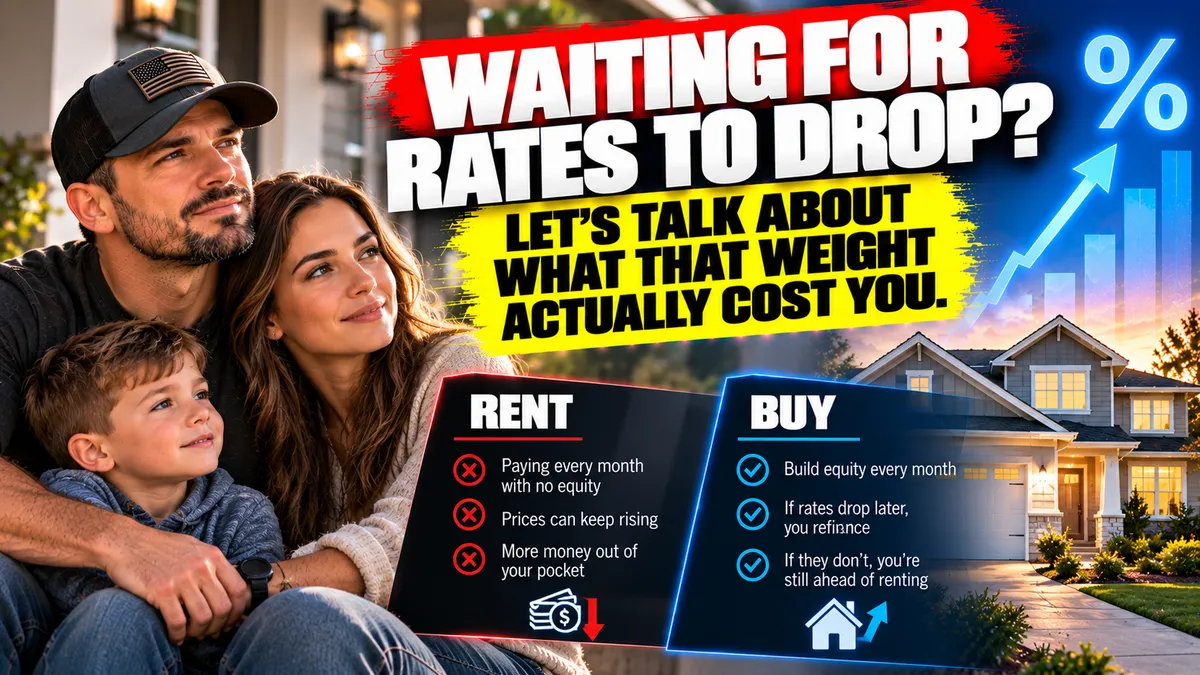
At the same time home prices in most markets have not been sitting still while buyers wait for a better rate environment. The property that costs three hundred and fifty thousand today may cost more by the time the rate environment feels comfortable enough to act on. The buyer who waited for a lower rate may end up paying more for the same home, eliminating the savings the wait was supposed to produce.
The Two Scenarios Worth Running Side by Side
If rates drop later you refinance. You keep the equity that has been building since you closed. You capture the lower rate at that point and your position is better than if you had waited because you already have the equity that renting never would have produced.
If rates do not drop in the timeframe you hoped for you are still ahead of where you would be if you had continued renting. The equity built through principal paydown and appreciation belongs to you. The rent paid during those same months belongs to someone else.
Travis runs this comparison with his clients regularly because the numbers tell a clearer story than the general feeling that waiting is safer. Seeing the actual dollar difference between buying now and waiting a year makes the decision concrete rather than conceptual.
What to Do Next
DM Travis Egan and he will run that comparison for your specific situation so the decision is grounded in real numbers. He is here to help. Semper Fi.
Sources
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
FannieMae.com
Investopedia.com