The Lowest Advertised Mortgage Rate Is Not Always the Best Loan and Here Is Why It Costs Buyers Thousands
Where Most Buyers Lose Money Without Realizing It
The instinct to find the lowest interest rate available and call it the best mortgage is understandable and it is where a significant number of buyers end up paying thousands more than they needed to. Travis Egan wants buyers to understand what is actually behind an advertised rate before any decision is made based on that number alone.
How Lenders Make a Rate Look Unbeatable
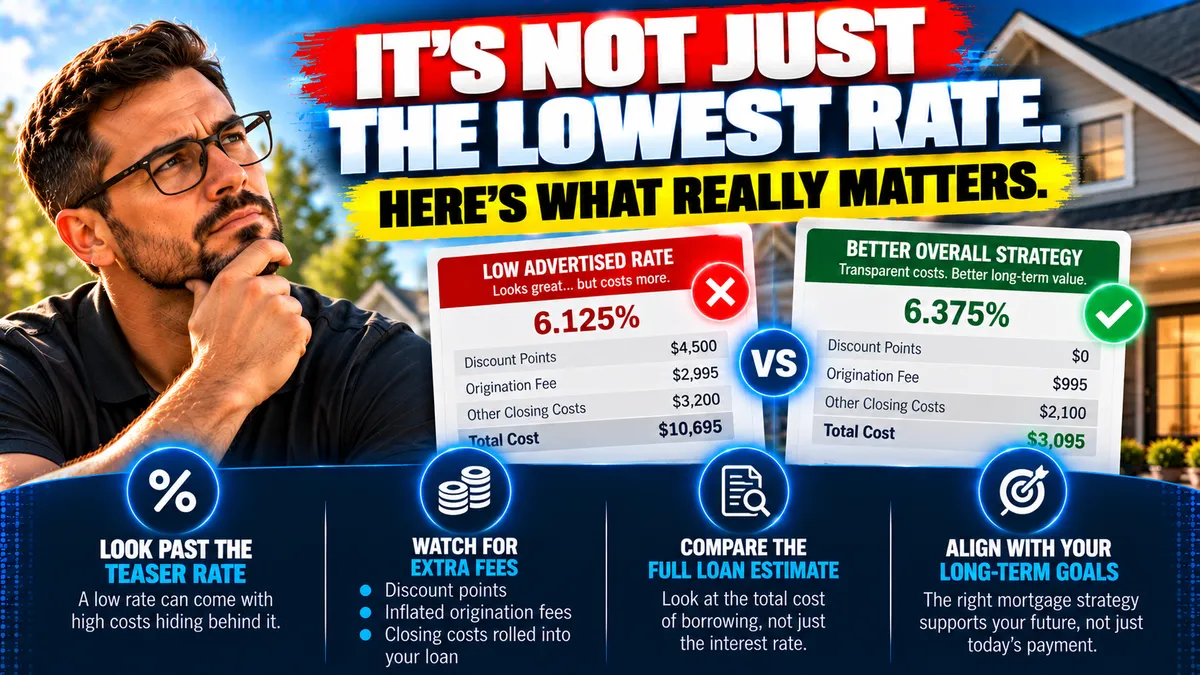
A lower interest rate can be manufactured through several mechanisms that most buyers do not examine closely. Discount points paid at closing buy down the rate. One point equals one percent of the loan amount paid upfront. On a four hundred thousand dollar loan each point is four thousand dollars. A rate that appears dramatically lower than a competitor’s may require two or three points to achieve it making the advertised number genuinely misleading as a comparison tool.
Inflated origination fees are another mechanism. These fees increase the lender’s profit margin on the loan while the rate stays low enough to attract attention. Closing costs can also be rolled directly into the loan balance which makes them invisible at closing while increasing the amount borrowed and the interest paid over the life of the loan.
The rate on the flyer reflects one carefully chosen number. The total cost of the loan is a different calculation entirely.
What a True Mortgage Strategy Actually Looks Like
Understanding the total cost of borrowing means looking at the interest rate alongside every fee, every point, and every cost that goes into getting the loan. The loan estimate that every lender is required to provide itemizes these costs and makes side-by-side comparison possible when buyers know what to look for.
Keeping closing expenses transparent rather than allowing them to disappear into the loan balance means the buyer actually understands what the financing costs rather than discovering it years later when the balance payoff surprises them.
Aligning the financing structure with long-term wealth goals means considering how long the buyer plans to stay in the loan before deciding whether paying points to buy down the rate makes financial sense. Points only pay off if the buyer stays in the loan long enough for the monthly savings to recover the upfront cost. A buyer who refinances or sells in three years likely should not be paying two points at closing regardless of how attractive the resulting rate looks.
What to Do Before You Lock Anything
Before locking in any loan look past the teaser rate and compare the full loan estimate. Message Travis Egan to break down your options with complete transparency so the comparison is based on total cost rather than the number on a flyer.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
BankRate.com