Still Paying PMI on a Conventional Loan When You Qualify for a VA Loan and Here Is What to Do
The Refinance Conversation That Is Worth Thousands a Year for Some Veterans
If you are a veteran or service member who bought your home with a conventional loan before you fully understood your VA loan eligibility there is a conversation worth having that could save you a meaningful amount of money every single year.
Travis Egan has had this conversation with veterans and service members who purchased their homes before they knew they were eligible for VA financing. The solution is a VA rate and term refinance that converts the existing conventional loan into a VA loan in a single transaction.
What This Move Actually Accomplishes
A VA rate and term refinance does two things simultaneously for eligible borrowers who currently have a conventional loan.
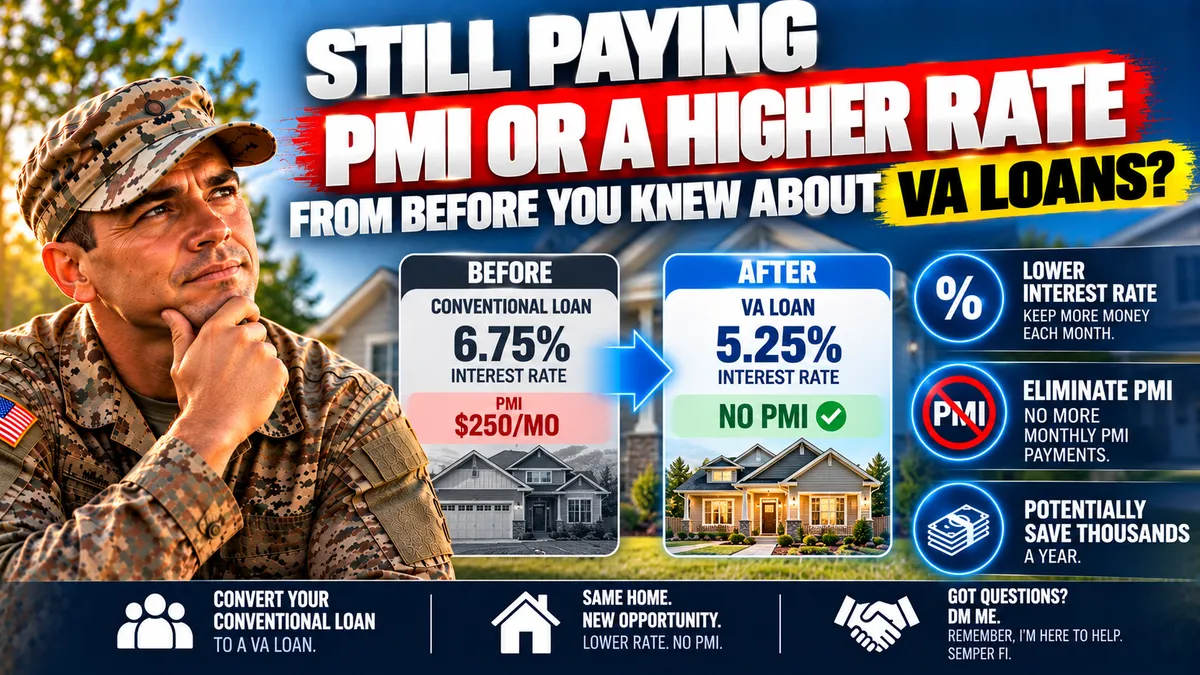
It can lower the interest rate to reflect what VA financing offers rather than what the conventional market required at the time of purchase. For veterans who bought before understanding their VA benefit that original rate may be meaningfully higher than what a VA loan would have produced.
It eliminates private mortgage insurance. PMI is a recurring monthly cost on conventional loans when the down payment was below twenty percent. VA loans do not require PMI regardless of the down payment amount. Converting a conventional loan to a VA loan removes that cost entirely from the monthly payment picture.
The combination of a lower rate and no PMI can produce a monthly savings that adds up to thousands of dollars annually depending on the loan amount and the original rate.
Why This Happens More Than People Realize
A significant number of veterans and service members buy their first home before they fully understand the VA loan benefit they earned through their service. They put money down, pay for PMI, and carry a higher rate without knowing that an alternative was available to them the entire time.
The eligibility did not expire. The benefit is still there. And a refinance can course correct the original decision even years later.
How to Find Out If This Applies to You
If you are currently paying PMI on a conventional mortgage and you are a veteran or active duty service member this conversation is worth having. DM Travis Egan directly with your situation and he will tell you whether a VA rate and term refinance makes sense for your specific loan and what the numbers actually look like.
He is here to help. Semper Fi.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com