Self-Employed Veterans Can Qualify for a VA Loan and Here Is What the Process Actually Requires
The Myth That Is Keeping Self-Employed Veterans Out of the Conversation
Travis Egan hears this one regularly from self-employed veterans and small business owners in the Clarksville area. The assumption that VA loan eligibility requires W-2 employment and that self-employed income disqualifies a veteran from using the benefit they earned. That assumption is wrong and Travis wants it corrected before it keeps one more self-employed veteran from exploring options they actually have.
What Self-Employed VA Borrowers Actually Need
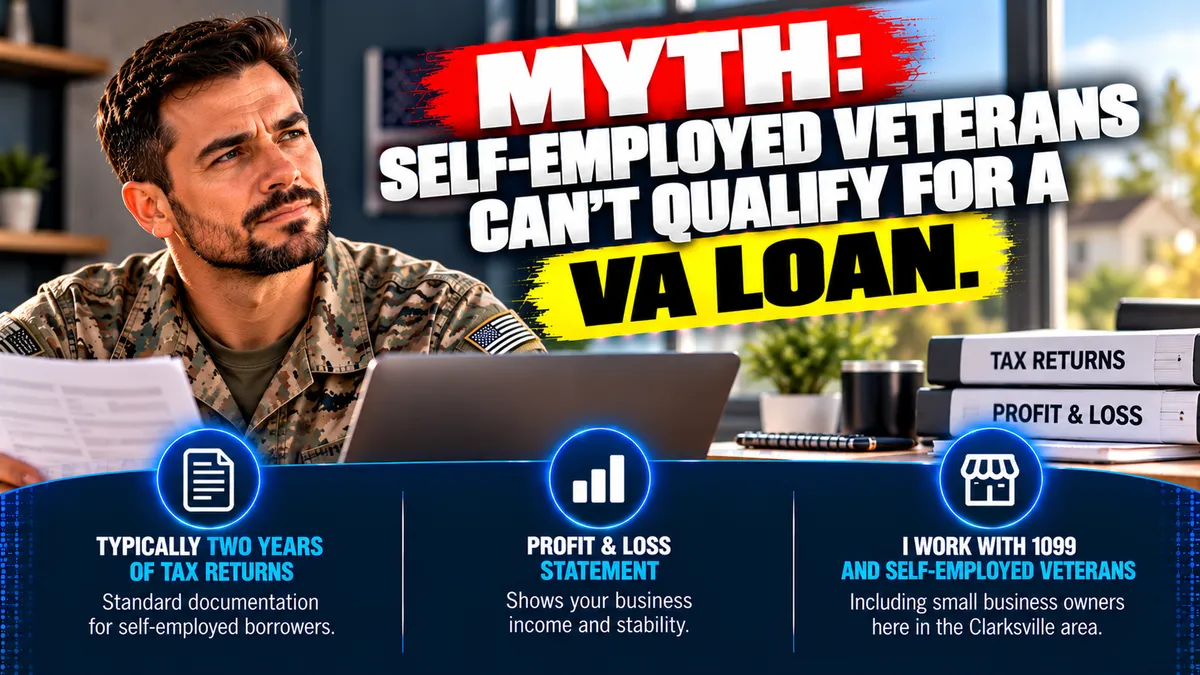
Qualifying for a VA loan as a self-employed borrower or a 1099 earner is not more impossible than it is for a W-2 employee. It is more paperwork. That is a meaningfully different thing.
The documentation process for self-employed VA borrowers typically requires two years of personal tax returns and a profit and loss statement. Those documents allow the lender to establish qualifying income in a way that reflects the borrower’s actual earnings rather than relying on pay stubs that do not exist for someone running their own business.
The income calculation from tax returns follows specific VA guidelines and the same benefit that applies to employed veterans applies fully to self-employed veterans who meet the income and eligibility requirements. The path to qualification is different. The destination is the same.
What Travis Does for Self-Employed Veterans
Travis works with 1099 earners and self-employed veterans regularly including small business owners throughout the Clarksville market. He knows what documentation is needed, how the income calculation works for self-employed borrowers under VA guidelines, and how to get a file organized correctly from the beginning so the process moves efficiently rather than stalling on documentation issues that could have been addressed upfront.
More paperwork is not a reason to walk away from a zero-down loan program with no PMI that a veteran earned through their service. DM Travis Egan directly with any questions about VA financing as a self-employed borrower. He is here to help. Semper Fi.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com