Your Home Equity Is Earning Zero Percent Return and Here Is What Strategic Homeowners Do Instead
The Conversation About Home Equity That Almost Nobody Is Having
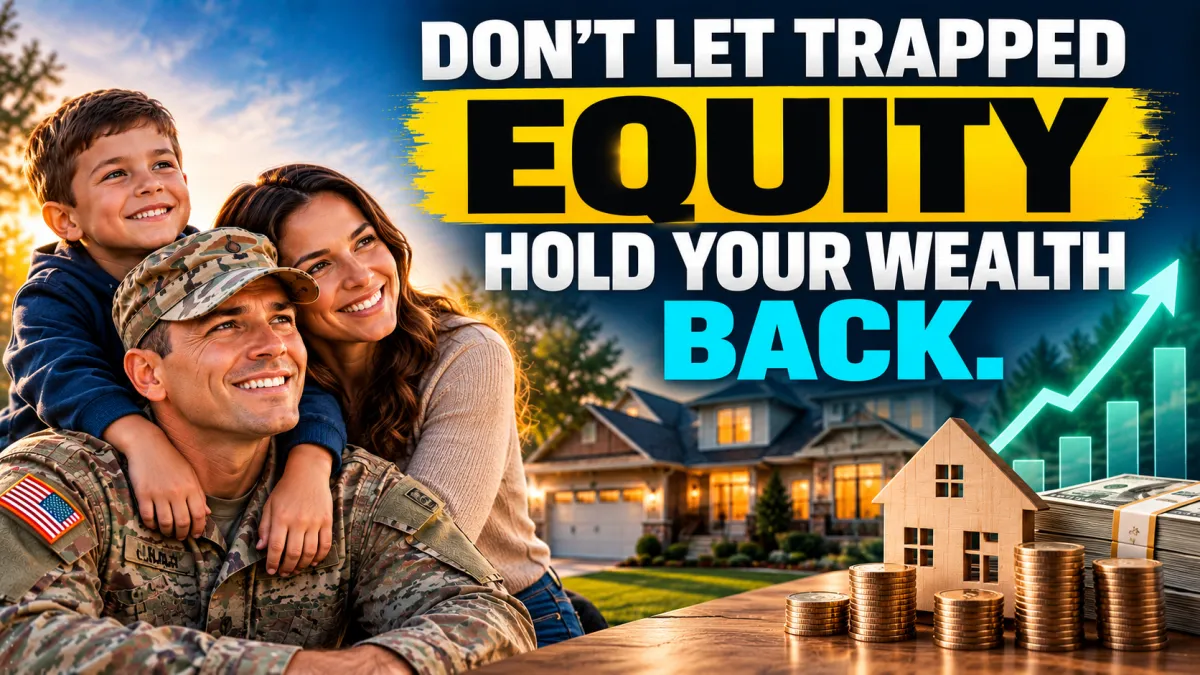
Homeowners celebrate when their home's value climbs. It feels like wealth building in real time, and in one sense, it is. But Travis Egan wants homeowners to understand something important about equity that sits idle inside a home's walls. It is not working. And leaving hundreds of thousands of dollars trapped in a non-performing asset may actually be holding your overall wealth back rather than building it.
What Idle Equity Actually Does
Equity sitting in your home earns exactly zero percent return on its own. It improves your net worth on paper. It looks good on a balance sheet. But it produces no cash flow in your everyday life, no compounding growth, and no return unless you access it and deploy it.
Most financial conversations collapse the distinction between net worth and accessible wealth into a single number. But a homeowner with four hundred thousand dollars in home equity and twenty thousand dollars in liquid savings is in a fundamentally different financial position than someone with the same four hundred thousand dollars in a diversified investment portfolio. The number looks identical on paper. The financial flexibility and earning potential are dramatically different.
What Strategic Homeowners Do Differently
Strategic homeowners treat equity as a working asset, not a number to be proud of. The question is not how much equity I have. It is what that equity is doing for me and what it could be doing instead.
Eliminating high-interest debt with equity that costs you nothing to hold but earns nothing in return is one of the most straightforward applications. Replacing an eighteen percent credit card balance with equity accessed at a fraction of that cost changes the monthly cash flow picture immediately and permanently, as long as the underlying debt behavior changes alongside it.
Funding a high-return investment property is another deployment path that strategic real estate investors use regularly. Equity in a primary residence becomes the down payment on a cash-flowing rental that generates income, appreciation, and tax advantages simultaneously. The equity did not disappear. It moved from a non-performing asset into a performing one.
Securing lower wholesale financing through a cash-out refinance or home equity product can also position a homeowner to access capital at rates far more favorable than other borrowing alternatives. That capital can then be deployed wherever the return justifies the cost of accessing it.
What Generational Wealth Actually Requires
Building real generational wealth is not just about accumulating equity. Every homeowner who bought in a rising market has accumulated equity without doing anything particularly strategic. Wealth that compounds and transfers across generations comes from knowing when and how to leverage equity safely, rather than letting it sit as a number that impresses nobody except the mortgage statement.
The word safely matters. Accessing equity without a clear deployment strategy and a clear understanding of the risk profile of what it is going into is not wealth building. It is speculation. The goal is purposeful leverage that produces a return meaningfully above the cost of accessing the capital.
If you want to see what your equity could actually be doing for you, reach out to Travis Egan to run the numbers on your specific situation.
Check out the previous video. IRRRL or VA Cash Out Refinance and Here Is How to Know Which One Actually Fits Your Situation.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
NationalFoundationForCreditCounseling.org