Why VA Loans Get Denied Is Rarely What Veterans Expect and Here Is the Most Common Reason
The Denial Nobody Saw Coming and How to Make Sure It Does Not Happen to You
Most veterans who start the VA loan process with solid credit and a clear path to approval assume the hard work is done once they get pre-approved. Travis Egan wants every VA buyer to understand that the period between pre-approval and closing is where deals fall apart and the reason is almost never what people expect.
What Actually Kills VA Loans in the Middle of the Process
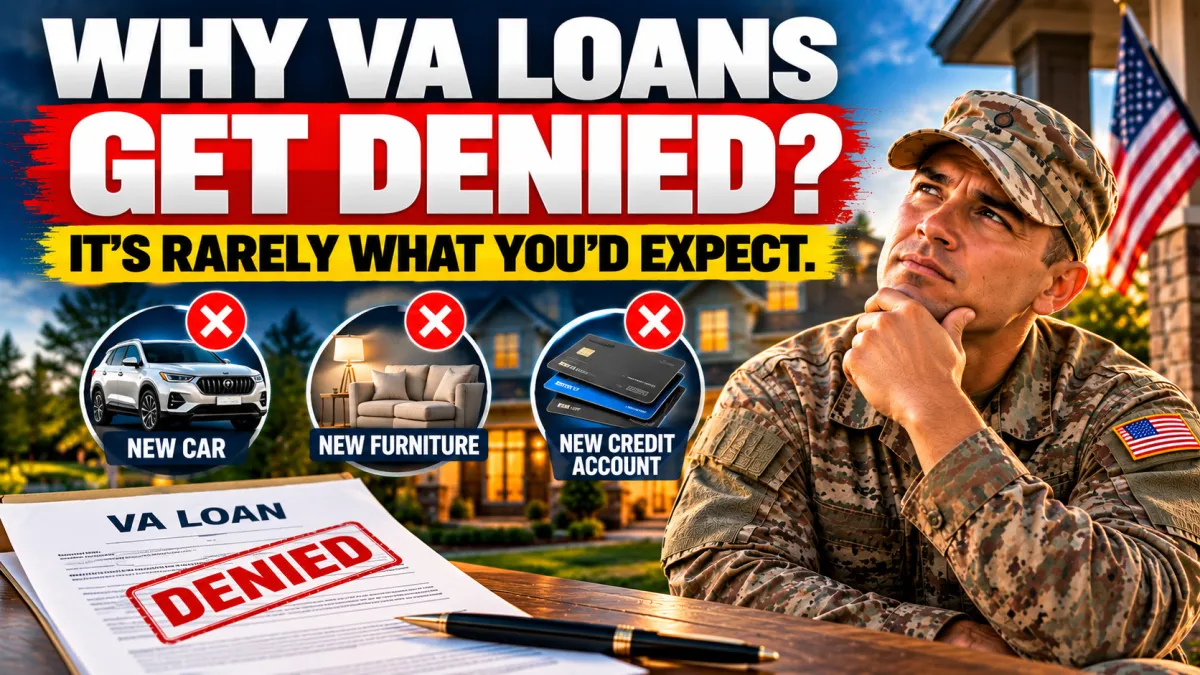
It is not a credit score problem. It is not an appraisal issue. The most common deal-killer Travis sees during the loan process is a major purchase or a new credit account opened after the loan has already started moving through underwriting.
A new car purchased while under contract. Furniture financed through a store credit account because the new house needs to be furnished. A new credit card opened to take advantage of a promotional offer. Any of these actions can change the debt-to-income ratio that was used to qualify the borrower in a way that pushes it outside the guidelines that approved the loan in the first place.
Why the Timing Makes It So Damaging
The debt-to-income ratio is a calculation that compares monthly debt obligations to monthly qualifying income. When a lender approves a VA loan they are approving it based on the financial picture that existed at the time of application. A new monthly payment from a car loan or a store credit minimum adds to the debt side of that equation and can push the ratio above the maximum allowed threshold.
When that happens close to the closing date the options available to resolve it are limited and sometimes nonexistent. The closing gets delayed. In some cases it gets derailed entirely. A transaction that was on track to close cleanly unravels because of a purchase decision that felt completely unrelated to the home loan.
The Rule Travis Egan Gives Every Client
Do not buy anything major until after you have keys in hand. Not a car. Not furniture on store credit. Not appliances financed through a retailer. Not a new credit card regardless of the rewards offer. Nothing that creates a new monthly payment or adds a new account to the credit profile until the loan has closed and the keys are in your possession.
It is a simple rule and it protects the entire transaction from a risk that is completely avoidable with a small amount of patience.
Got questions about what to do or not do during the VA loan process? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
ConsumerFinancialProtectionBureau.gov
MilitaryOneSource.mil
MortgageNewsDaily.com
Investopedia.com