The Myth That You Have to Wait Years to Refinance a VA Loan and What the Timeline Actually Is
The Misconception That Is Keeping Veterans From a Rate Improvement They Could Already Access
Veterans are being told they have to wait years before they can refinance their VA loan. It is a misconception that is costing some veterans meaningful money by keeping them in a higher rate when the timeline to refinance is actually much closer than they were led to believe.
Travis Egan wants to set the record straight.
What the Seasoning Requirement Actually Is
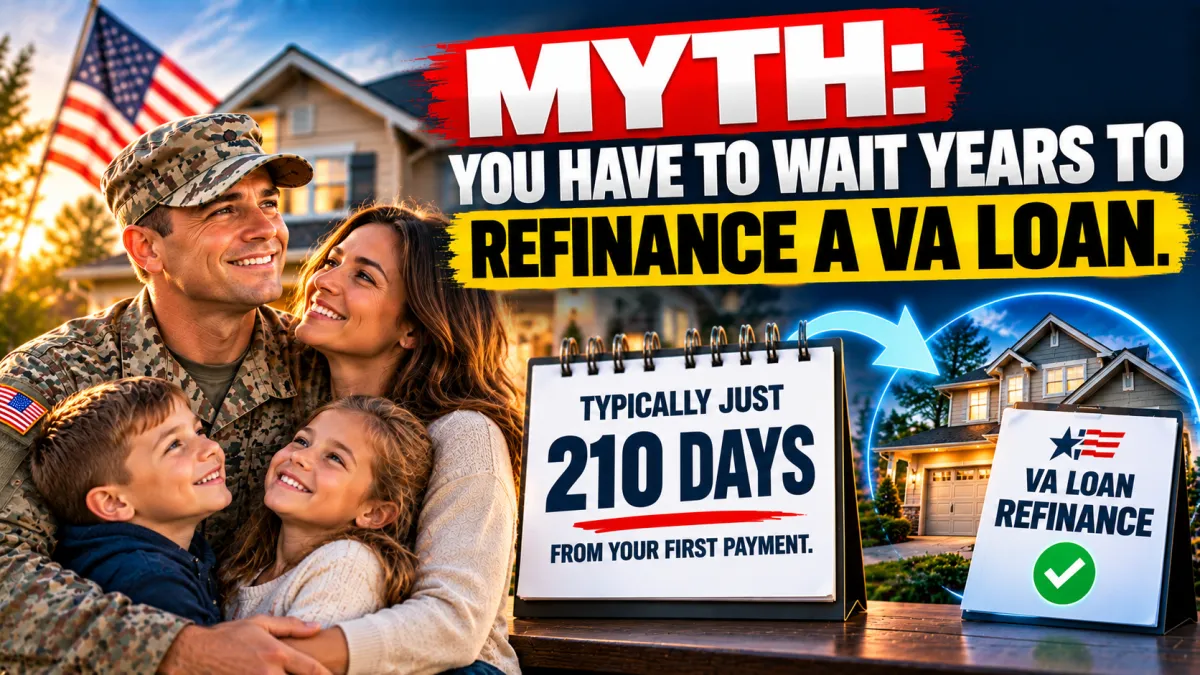
The standard seasoning requirement for a VA Interest Rate Reduction Refinance Loan is typically two hundred and ten days from the date of the first payment on the existing loan. Not two years. Not several years. Two hundred and ten days.
That is approximately seven months from the first mortgage payment. For a veteran who closed on a purchase and made their first payment in January the refinance window under standard guidelines can open as early as August of the same year.
Travis has helped clients refinance within their first year of ownership when rates moved in their favor during that window. The timeline exists not as a barrier but as a basic seasoning threshold that ensures the loan has enough payment history to qualify for the streamline refinance process.
Why This Matters Right Now
If rates improve in the months following a purchase a veteran who was told they cannot refinance yet may actually be closer to eligibility than they realize. The difference between waiting another twelve or eighteen months under a higher rate and refinancing at seven months can be thousands of dollars depending on the loan amount and the rate differential involved.
The conversation about whether a refinance makes sense involves the seasoning timeline, the current rate versus the available refinance rate, and the break-even calculation that determines whether the cost of refinancing is justified by the monthly savings. All of those factors need to be evaluated together rather than simply accepting a general statement that refinancing is not an option yet.
What to Do If Someone Told You to Wait
If you were told refinancing is not an option yet the math on your actual timeline is worth checking before accepting that answer. The two hundred and ten day seasoning requirement is the standard threshold and your situation may be closer to meeting it than you think.
Got questions about VA refinance timing or whether an IRRRL makes sense for your specific situation? DM Travis Egan directly. He is here to help. Semper Fi.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com